The Finance Act 1991 (Commencement and Transitional Provisions) Order 1993
S.I. 1993/1152 · Made 26 April 1993
CUSTOMS AND EXCISE
Made 26th April 1993
The Commissioners of Customs and Excise, in exercise of the powers conferred on them by section 7 of the Finance Act 1991f1 and of all other powers enabling them in that behalf, hereby make the following Order:
Annotations to the whole text
Footnotes
- f1
Contents
- 1Citation
- 2Interpretation
- 3Commencement
- 4Saving provisions
- 5Charge of duty on beer held on registered premises etc.
- 6Transitional provisions – records
- 7Transitional provisions – relief
- 8Transitional provisions – relief
- Signature
- Schedule 1: COMMENCEMENT
- IPROVISIONS OF THE ACT COMING INTO FORCE ON 1ST MAY 1993
- IIPROVISIONS OF THE ACT COMING INTO FORCE ON 1ST JUNE 1993
- Schedule 2Schedule 2
- Explanatory note
1Citation
This Order may be cited as the Finance Act 1991 (Commencement and Transitional Provisions) Order 1993.
2Interpretation
In this Order–
-
“the Act” means the Finance Act 1991;
-
“the 1979 Act” means the Alcoholic Liquor Duties Act 1979f1;
-
“brewing record” has the meaning given by regulation 2 of the Beer Regulations 1985f2;
-
“entered premises of a brewer for sale” has the same meaning as it has in regulation 4 of the spoilt beer Regulations;
-
“registered holder” means any person registered under section 41A of the 1979 Act;
-
“registered premises” means any premises registered under section 41A or section 47 of the 1979 Act;
-
“the relevant time” means 12.01 a.m. on 1st June 1993;
-
“spoilt beer Regulations” means the Spoilt Beer (Remission and Repayment of Duty) Regulations 1987f3;
-
“unfinished” in relation to any beer means beer in any stage of production before it has reached that state of maturity at which it is fit for consumption.
Subject to paragraph (1) above and unless the context otherwise requires, words and expressions in this Order have the same meaning as they have in the 1979 Act.
3Commencement
The provisions of the Act specified in the first column of Part I of Schedule 1 to this Order shall come into force on 1st May 1993.
The provisions of the Act specified in the first column of Part II of Schedule 1 to this Order, insofar as they are not already in force, shall come into force on 1st June 1993.
4Saving provisions
Notwithstanding the effect of any provision brought into force by article 3(1) above which affects the 1979 Act, and without prejudice to article 7(4) below–
sections 46, 47 and 48 of the 1979 Act (before substitution of new provisions in accordance with section 7 of, and Schedule 2 to the Act); and
any orders, regulations or notices made under any power conferred by a provision of the 1979 Act which are in force on 30th April 1993,
shall remain fully in force until the relevant time.
Where on or after 1st June 1993 it is necessary (for any purpose) to ascertain the original gravity of beer which was produced or was in the process of production before that date, regulation 14 of, and Schedule 1 to, the Beer Regulations 1985 shall continue to have effect notwithstanding any provision brought into force by this Order or any provisions in any statutory instrument revoking those Regulations.
5Charge of duty on beer held on registered premises etc.
For the purpose of the charge of excise duty on beer, any beer (including unfinished beer) which is–
produced, or in the process of being produced, before 1st June 1993; and
held on, or in the process of being transported between, registered premises at the relevant time,
shall be treated as beer produced on 1st June 1993.
6Transitional provisions – records
Every registered brewer and every registered holder who intends to make a claim for relief in accordance with the provisions of this Order or who holds beer in respect of which another person may be eligible to make such a claim for relief shall make a record of that beer (including unfinished beer) held on his registered premises at the relevant time.
The record mentioned in paragraph (1) above shall contain the following particulars–
the descriptions of the beer;
the packaging or vessels in which each description of beer is contained;
the location within the registered premises of each description of beer;
the quantity in litres of each description of beer;
the original gravity–
at the relevant time; and
(in the case of beer brewed in the United Kingdom) contained in the brewing record or (in any other case) declared to the Commissioners in accordance with section 40 of the 1979 Act,
of each description of beer;
the date upon which the original gravity was entered in the brewing record or, as the case may be, declared to the Commissioners in accordance with section 40 of the 1979 Act;
the actual rate of duty charged on the beer;
the effective rate of duty charged on the beer; and
the amount of relief (if any) which may be claimed.
The particulars of packaging or vessels shall include details of the size and type of any keg, cask, bottle, can or other vessel except that, in the case of vessels used in the brewing of beer, the identifying marks of those vessels shall constitute a sufficient description for the purposes of paragraph (2)(b) above.
The particulars of location shall include the address of the registered premises and the location of the beer within those premises.
Subject to paragraph (6) below, the original gravity mentioned in paragraph (2)(e)(i) above shall be ascertained in accordance with regulation 14(3) of the Beer Regulations 1985 provided that, if it is impracticable to use that method the particulars may be determined either–
in accordance with regulation 14(1) of the Beer Regulations 1985 (but any fraction of a degree shall be ignored); or
in accordance with any other method which the Commissioners may allow.
In the case of beer which has not been diluted or mixed with other beer since the original gravity mentioned in paragraph (2)(e)(ii) above was determined, the original gravity mentioned in paragraph (2)(e)(i) above shall not be ascertained or determined in accordance with paragraph (5) above but shall be presumed to be that which was entered in the brewing record or, as the case may be, declared to the Commissioners in accordance with section 40 of the 1979 Act.
The effective rate of duty shall be calculated by taking into account actual losses during production, processing, blendings and dilutions.
7Transitional provisions – relief
Beer which–
is produced or unfinished before 1st June 1993; and
is held on registered premises at the relevant time,
shall be eligible for relief from duty which was charged before 1st June 1993 in accordance with the provisions of this Order provided that the beer in question is incapable of being the subject of a claim for remission or repayment of duty in accordance with the spoilt beer Regulations and provided that no other claim for relief has been made in relation to it.
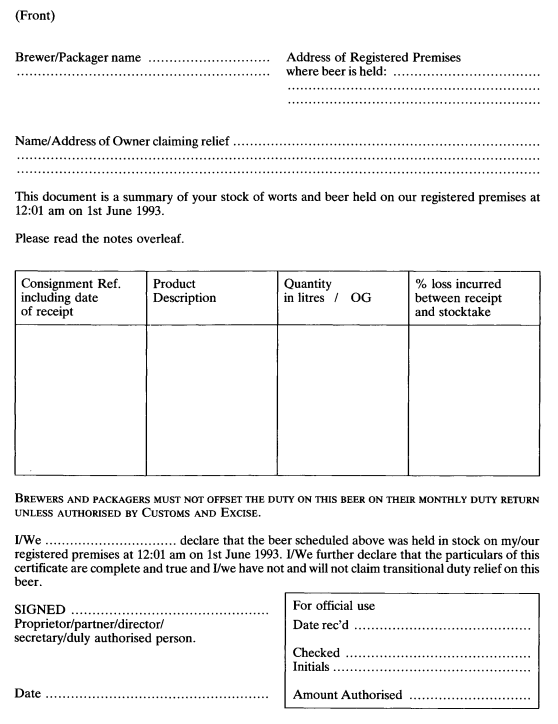
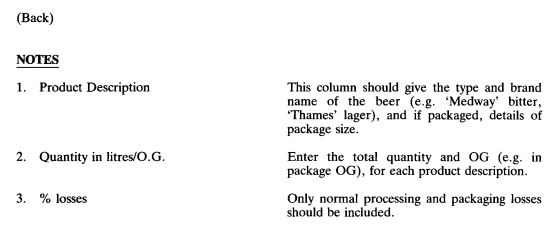
A registered brewer or registered holder who holds on his registered premises at the relevant time beer which is eligible for relief from duty may make a claim for relief; provided that, if that beer is owned by a person other than that registered brewer or registered holder, any claim for relief shall be made by the owner of that beer and shall be accompanied by a certificate (in the form numbered 2 set out in Schedule 2 to this Order or in a form to the like effect) given by the registered brewer or registered holder who would, apart from this proviso, be entitled to claim the relief in question.
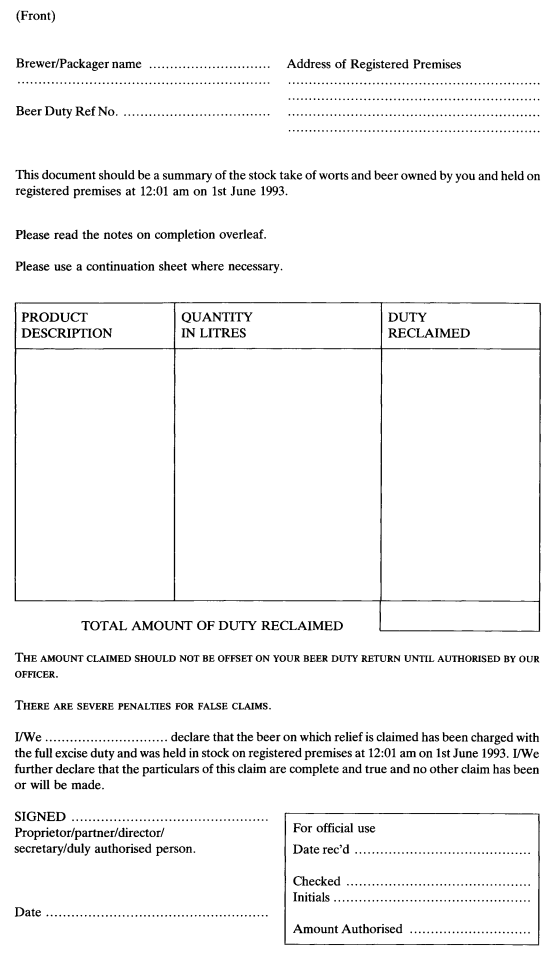
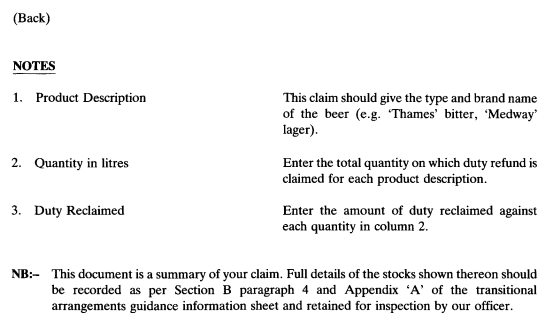
Any claim for relief shall be made in the form numbered 1 set out in Schedule 2 of this Order or in a form to the like effect.
The spoilt beer Regulations shall continue to have effect, notwithstanding the effect of any provision brought into force by article 3 of this Order, in relation to any beer which is not eligible for relief under this Order and which was removed from the entered premises of a brewer for sale before 1st June 1993.
Beer which is in the process of being transported between registered premises at the relevant time shall, for the purposes of claims for relief, be treated as if it were held on the registered premises from which it was consigned provided that–
the record mentioned in article 6(1) above (with the exception of the particulars mentioned in article 6(2)(c) above) is made for such beer; and
the person making the claim for relief satisfies the Commissioners that the beer has been charged with duty in accordance with article 5 above.
8Transitional provisions – relief
Where in accordance with article 7 above the Commissioners are in receipt of a claim for relief they shall grant the relief claimed provided they are satisfied–
that the claim is accurate in every respect and that no other claim has been made in respect of the beer;
unless the Commissioners otherwise allow, the claim was received no later than 1st October 1993; and
the amount of relief claimed does not exceed the amount of duty actually charged on the beer in question.
Where relief is granted in accordance with paragraph (1) above the person claiming it may offset the amount of relief granted against the amount of duty payable by him to the Commissioners and shown on any return of duty which he may be liable to make after 1st July 1993.
Where the person claiming relief is for any reason unable to offset the amount of relief granted in the manner specified in paragraph (2) above the Commissioners may make payment of that relief by such other means as appears to them to be appropriate.
Signature
Leonard Harris
Commissioner of Customs and Excise
New King’s Beam House 22 Upper Ground London SE1 9PJ
26th April 1993
IPROVISIONS OF THE ACT COMING INTO FORCE ON 1ST MAY 1993
| Provisions of the Act | Subject matter of provisions |
|---|---|
| section 7(2) and (3) | Registration of persons who may hold and premises where beer may be held without payment of duty; registration of producers of beer |
| section 7(5) and Schedule 2 except paragraphs 1, 2, 3(3), 4, 5(2), 6 to 12 and 15 to 24 | Amendment of enactments and instruments relating to beer duty |
IIPROVISIONS OF THE ACT COMING INTO FORCE ON 1ST JUNE 1993
| Provisions of the Act | Subject matter of provisions |
|---|---|
| section 7 | Beer duty |
| Schedule 2 | Amendment of enactments and instruments relating to beer duty |
Schedule 2
FORM 1
BEER DUTY:– TRANSITIONAL RELIEF CLAIM
FORM 2
BEER DUTY:– TRANSITIONAL RELIEF CERTIFICATE
Explanatory note
(This note is not part of the Order)
This Order brings into force on 1st May 1993 certain provisions of section 7 of, and Schedule 2 to, the Finance Act 1991. These provisions relate to the registration of persons who may hold, and premises where beer may be held, without payment of duty, and the registration of producers of beer.
The Order makes transitional and saving provisions for certain sections of the Alcoholic Liquor Duties Act 1979 and for the subordinate legislation made thereunder.
It provides that all beer which is produced, or in the process of being produced before 1st June 1993, and which is held on registered premises or is in the process of being transported between registered premises at 12.01 a.m. on 1st June 1993, shall be treated as beer produced on 1st June 1993. Such beer, which will be charged with duty under the end product system, will be eligible, subject to certain conditions, for relief from the duty charged before 1st June 1993.
The Order provides for a claims procedure and for the records required to be kept for relief purposes.
It further brings into force on 1st June 1993 the remaining provisions of section 7 of, and Schedule 2 to, the Finance Act 1991. These provisions relate to beer duty and its control, and amend various Acts connected with beer duty.