The Value Added Tax, etc (Correction of Errors, etc) Regulations 2008
S.I. 2008/1482 · Made 9 June 2008
Value Added Tax
Insurance Premium Tax
Excise
Landfill Tax
Climate Change Levy
Aggregates Levy
Made 9th June 2008
Laid before the House of Commons 10th June 2008
Coming into force 1st July 2008
The Commissioners for Her Majesty’s Revenue and Customs make the following Regulations exercising the powers conferred by Schedule 11 paragraphs 2(1), 2(10) and 2(11) to the Value Added Tax Act 1994f1, sections 54, 74(7) and 74(8) of the Finance Act 1994f2 and also sections 38(1) and 42(2) of that Actf3, sections 49, 71(8) and 71(9) of the Finance Act 1996f4, Schedule 6 paragraphs 41(1), 41(2) and 146(7) to the Finance Act 2000f5, and sections 25(1), 25(2) and 45(5) of the Finance Act 2001f6:
Annotations to the whole text
Footnotes
- f1
-
1994 c. 23; Schedule 11 paragraph 2(1) was amended by the Finance Act 2002 (c. 23) sections 24(1)(b)(ii), 24(5) and 141 and Schedule 40 Part 2(2), and S.I. 2003/3043 (C. 114). Schedule 11 paragraph 2(10) was amended by the Finance Act 1996 (c. 8) sections 38(1) and 38(3). Although section 96(1) defines “regulations” as those made by “the Commissioners” (of Customs and Excise) under the Act, section 50(1) of the Commissioners for Revenue and Customs Act 2005 (c. 11) provides for the latter to be taken as a reference to the Commissioners for Her Majesty’s Revenue and Customs.
- f2
-
1994 c. 9; sections 54, 74(7) and 74(8) of the Act relate to insurance premium tax, and sections 74(2) and 73(1) provide for relevant regulations to be made by “the Commissioners” (of Customs and Excise) (about which see footnote (a) above).
- f3
-
Sections 38(1) and 42(2) of the Act relate to air passenger duty, and section 42(1) defines “regulations” as those made by “the Commissioners”. The latter refers to those for Her Majesty’s Revenue and Customs given section 43(4) of the Act and section 1(1) of the Customs and Excise Management Act 1979 (c. 2), the latter as amended by Schedule 4 paragraph 22(b) to the Commissioners for Revenue and Customs Act 2005 (c. 11).
- f4
-
1996 c. 8; sections 71(2) and 70(1) provide for regulations about landfill tax to be made by “the Commissioners” (of Customs and Excise) (about which see footnote (a) above).
- f5
-
2000 c. 17; Schedule 6 paragraph 41(1) was amended by the Finance Act 2003 (c. 14) sections 192(1), 192(2) and 216, and Schedule 43 Part 4(2). Schedule 6 paragraph 147 defines “the Commissioners” for climate change levy purposes as those of Customs and Excise (about which see footnote (a) above).
- f6
-
2001 c. 9; section 48(1) defines “the Commissioners” for aggregates levy purposes as those of Customs and Excise (about which see footnote (a) above).
Contents
- 1Citation and commencement
- 2Value added tax
- 3Insurance premium tax
- 4Air passenger duty
- 5Landfill tax, climate change levy, aggregates levy
- 6Landfill tax, climate change levy, aggregates levy
- 7Landfill tax, climate change levy, aggregates levy
- 8Landfill tax, climate change levy, aggregates levy
- Signature
- Schedule 1Insurance premium tax returns
- Schedule 2Air passenger duty return
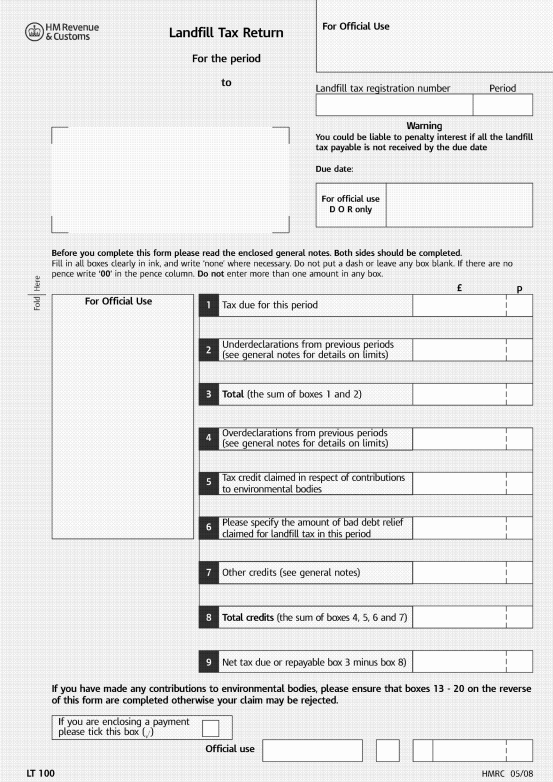
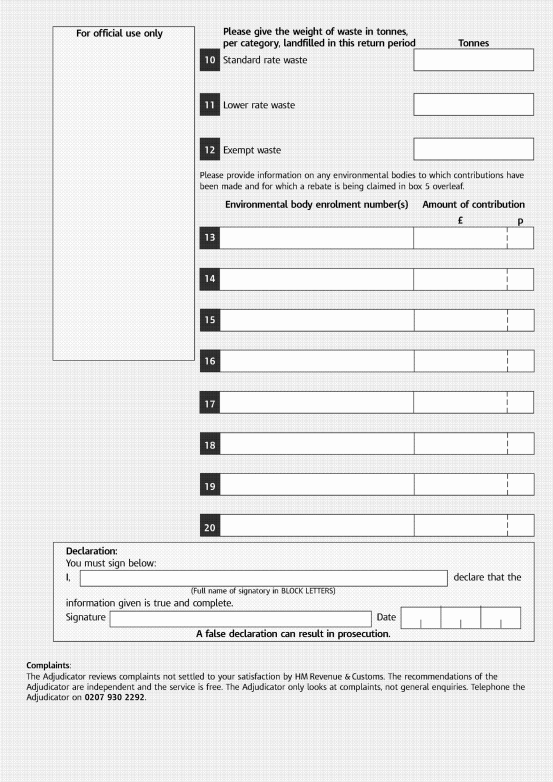
- Schedule 3Landfill tax return
- Explanatory note
1Citation and commencement
These Regulations may be cited as the Value Added Tax, etc (Correction of Errors, etc) Regulations 2008 and come into force on 1st July 2008.
2Value added tax
In regulation 34(3) of the Value Added Tax Regulations 1995f1 (the VAT Regulations) for “£2,000” substitute “£50,000”, then after “regulation.” start a new line and continue—
“But if Box 6 of the taxable person’s return for the prescribed accounting period must contain a total less than £5,000,000, the difference must not for these purposes exceed 1% of that total unless the difference is less than £10,000.
(Box 6 must contain the total value of sales and all other outputs excluding any VAT – see regulation 25 and Schedule 1 Forms 4 and 5.)”.
These amendments only have effect in relation to the overstatements or understatements of liability to VAT in regulation 34(3) of the VAT Regulations which taxable persons first discover during their prescribed accounting periods that begin on 1st July 2008 or later.
(See regulations 34(1) to 34(3) of the VAT Regulations for the meaning carried by “overstatements or understatements”; sections 96(1) and 3 of the Value Added Tax Act 1994f2 for, respectively, “VAT” and “taxable person”; regulations 2(1), 25 and 99(1) of the VAT Regulations for the meaning carried by “prescribed accounting period”.)
3Insurance premium tax
In regulation 13(3) of the Insurance Premium Tax Regulations 1994f1 (the IPT Regulations)—
for each “£2,000”, substitute “£50,000”;
for “the box opposite the legend “Overdeclarations from previous periods””, substitute “Boxes 6 to 8 (overdeclarations), as appropriate,”;
for “the box opposite the legend “Underdeclarations from previous periods””, substitute “Boxes 3 and 4 (underdeclarations), as appropriate,”;
then, after “accordingly.”, start a new line and continue—
“But if Box 10 of the registrable person’s return for the accounting period requires an entry for net value of taxable premiums (excluding tax) that is less than £5,000,000 (see regulation 12 and Forms 4 and 5 in the Schedule), the total mentioned in sub-paragraph (a) or (b) must not for these purposes exceed 1% of that net value unless the respective total is less than £10,000.”.
In regulation 13(4) of the IPT Regulations, omit in both places “not exceeding £2,000”.
Substitute the forms in Schedule 1 as, respectively, Form 4 (IPT 100) and Form 5 (IPT 100L) in the Schedule to the IPT Regulations (insurance premium tax returns).
The amendments in paragraphs (1) and (2) only have effect in relation to the overdeclarations or underdeclarations in regulation 13(3) of the IPT Regulations which registrable persons first discover in their accounting periods that begin on 1st July 2008 or later.
Those in paragraph (3) only have effect in respect of or as regards accounting periods that begin on 1st July 2008 or later.
(See regulation 13(1) of the IPT Regulations for the meaning of “overdeclaration” and “underdeclaration”; section 73(3A) of the Finance Act 1994f2 for “registrable person”; regulation 2(1) of the IPT Regulations for the meaning of “accounting period”.)
4Air passenger duty
Substitute the form in Schedule 2 for the one set out in Schedule 3 to the Air Passenger Duty Regulations 1994f1 (the APD Regulations) (Form APD 2 – air passenger duty return).
This amendment only has effect in relation to accounting periods that end on 31st July 2008 or later.
(See regulations 2(1) and 9(1) of the APD Regulations for the meaning carried by “accounting period”.)
5Landfill tax, climate change levy, aggregates levy
Omit regulation 13(3) of the Landfill Tax Regulations 1996f1 (the LT Regulations).
Insert “overdeclarations or”—
in regulation 13(4)(a) of the LT Regulations after “more”;
in regulation 13(4)(b) of the LT Regulations, in each place, after “those”;
in the full out words to regulation 13(4) of the LT Regulations after “enter the”.
In regulation 13(4)(b) of the LT Regulations—
for “of any overdeclarations”, substitute “respectively of any underdeclarations or overdeclarations”;
for “£2,000”, substitute “£50,000”.
In regulation 13(4) of the LT Regulations, for everything from “the box opposite” to “general notes)”.” substitute “Box 2 (underdeclarations) or Box 4 (overdeclarations), as appropriate (see Form 5 in the Schedule).”.
Then start a new line and continue—
“But if the registrable person’s VAT turnover is small, the total mentioned in sub-paragraph (b) must not for these purposes exceed 1% of that turnover unless the total is less than £10,000.
And if that person is not registered for VAT, the total mentioned in sub-paragraph (b) must not for these purposes exceed £10,000.”.
In regulation 13(5) of the LT Regulations, omit “(3) or”.
Substitute the form in Schedule 3 as Form 5 in the Schedule to the LT Regulations (landfill tax return).
The amendments in paragraphs (1) to (5) (and the related amendment in regulation 8) only have effect in relation to overdeclarations or underdeclarations in regulation 13 of the LT Regulations which registrable persons first discover in their accounting periods that begin on 1st July 2008 or later.
That in paragraph (6) only has effect in relation to returns that relate to periods that begin on 1st July 2008 or later.
(See regulation 13(1) of the LT Regulations for the meaning of “overdeclaration” and “underdeclaration”; section 47(10) of the Finance Act 1996f2 for “registrable person”; regulations 2(1) and 11 of the LT Regulations for the meaning carried by “accounting period” and “return”.)
6Landfill tax, climate change levy, aggregates levy
In regulations 14(2)(b), 17(3)(b) and 28(4) of, and Schedule 1 paragraph 8(2)(b) to, the Climate Change Levy (General) Regulations 2001f1 (the CCL Regulations), for each “£2,000” substitute “£50,000”.
After regulation 28(4) of the CCL Regulations, insert—
“(4A)But if the registrable person’s VAT turnover is small, each aggregate in paragraph (4) must not for those purposes exceed 1% of that turnover unless the aggregate is less than £10,000.
And if that person is not registered for VAT, each aggregate must not for those purposes exceed £10,000.”.
In regulation 28(5) of the CCL Regulations, for “paragraph (4)” substitute “paragraphs (4) and (4A)”.
These amendments (and the related amendment in regulation 8) only have effect in relation to under-calculations or over-calculations respectively in regulations 28(2) and 28(3) of the CCL Regulations which registrable persons first discover in their accounting periods that start on 1st July 2008 or later.
(See regulation 28(4) of the CCL Regulations for the meaning of “under-calculation” and “over-calculation”; regulation 2(1) of the CCL Regulations for the meaning of “registrable person”; regulation 3 of the CCL Regulations for the meaning carried by “accounting period”.)
7Landfill tax, climate change levy, aggregates levy
In regulations 15(4)(b), 18(3)(b) and 29(6) of the Aggregates Levy (General) Regulations 2002f1 (the AL Regulations), for each “£2,000” substitute “£50,000”.
Then, in regulation 29(6) of the AL Regulations, start a new line and continue—
“But if the registrable person’s VAT turnover is small, this total must not for these purposes exceed 1% of that turnover unless the total is less than £10,000.
And if that person is not registered for VAT, the total net amount must not for these purposes exceed £10,000.”.
These amendments (and the related amendment in regulation 8) only have effect in relation to under-calculations or over-calculations respectively in regulations 29(2) and 29(3) of the AL Regulations which registrable persons first discover in their accounting periods that start on 1st July 2008 or later.
(See regulation 29(4) of the AL Regulations for the meaning of “under-calculation” and “over-calculation”; regulation 2 of the AL Regulations for the meaning of “registrable person”; regulation 5 of the AL Regulations for the meaning carried by “accounting period”.)
8Landfill tax, climate change levy, aggregates levy
In regulation 13(4) of the LT Regulations as amended by regulations 5(2) to 5(4), regulation 28(4A) of the CCL Regulations inserted by regulation 6(2), and regulation 29(6) of the AL Regulations as amended by regulations 7(1) and 7(2), in each case after “exceed £10,000.” start a new line and continue—
“The VAT turnover is small only if Box 6 of that person’s value added tax return for the prescribed accounting period in which the discovery is made must contain a total less than £5,000,000 (total value of sales and all other outputs excluding any value added tax).
(See sections 96(1) and 1 of the Value Added Tax Act 1994 for “VAT” and “value added tax”, and sections 96(2) and 3 of and Schedules 1 to 3A to that Actf1 about being registered for VAT; regulations 2(1) and 25 of and Schedule 1 Forms 4 and 5 to the Value Added Tax Regulations 1995 for the meaning carried by “Box 6” and “return”; sections 96(1) and 25(1) of that Act and regulations 2(1), 25 and 99(1) of those Regulations for the meaning carried by “prescribed accounting period”; section 24(2) of that Act for “output tax”.)”.
Signature
Mike Eland
Mike Hanson
Two of the Commissioners for Her Majesty’s Revenue and Customs
9th June 2008
Schedule 1Insurance premium tax returns


Schedule 2Air passenger duty return


Schedule 3Landfill tax return
Explanatory note
(This note is not part of the Regulations)
These Regulations change how errors may be corrected in returns for VAT, insurance premium tax, landfill tax, climate change levy and aggregates levy. They also change the required form for air passenger duty returnsf1.
Regulation 2 increases to £50,000f2 the limit for self-correcting a net error in the VAT accountf3. But if the then VAT turnover is less than £5,000,000, the limit is 1% of that turnover (except where the net error is less than £10,000). The limits apply to net errors first discovered in VAT accounting periods starting on 1 July 2008 or later. (A penalty for the error may still be payablef4.)
Regulation 3 makes corresponding provision in the context of insurance premium tax and changes the required forms for returnsf5.
Regulations 5 and 8 align the position for and make corresponding provision in the context of landfill taxf6. If there is no turnover for VAT purposes, the limit is £10,000. The required form for returns is changed.
A full and final Impact Assessment of the effect that this instrument will have on the costs of business and the voluntary sector is available at www.hmrc.gov.uk and is annexed to the Explanatory Memorandum which is available alongside the instrument on the OPSI website.