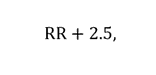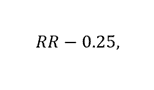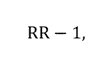The Taxes (Interest Rate) (Amendment No. 2) Regulations 2020
S.I. 2020/995 · Made 15 September 2020
Original text. legislation.gov.uk does not revise statutory instruments, so later amendments are not shown here. Changes made to it are listed under each provision when known.
Digital Services Tax
Made 15th September 2020
Laid before House of Commons 16th September 2020
Coming into force 14th October 2020
The Treasury make the following Regulations in exercise of the powers conferred by section 178(1), (2)(w) and (3) of the Finance Act 1989f1.
Annotations to the whole text
Footnotes
f1
1989 c.26; paragraph (w) of section 178(2) was inserted by paragraph 2 of Schedule 10 to the Finance Act 2020 (c.14) and section 178(3)(f) was amended by s.88(2)(b) of the Finance Act 2019 (c.1).
The Taxes (Interest Rate) Regulations 1989f1 are amended as follows.
(2)
In the definition of “operative date” and “reference date” in regulation 2(1) (interpretation), after “3ZA” insert “, 3ZD”.
(3)
After regulation 3ZB insert—
“Applicable rate of interest on overdue digital services tax
3ZC.
(1)
For the purposes of section 67(1) of the Finance Act 2020f2, the rate applicable under section 178 shall, subject to paragraph (2), be 2.6% per annum.
(2)
Where on a reference date after 14th October 2020 the reference rate found on that date differs from the established rate, the rate applicable under section 178 for the purposes mentioned in paragraph (1) shall, on and after the next operative date, be the percentage per annum found by applying the formula specified in paragraph (3).
(3)
The formula specified in this paragraph is–
where RR is the reference rate referred to in paragraph (2).
Applicable rate of interest on overpaid digital services tax
3ZD.
(1)
For the purposes of section 68(1) of the Finance Act 2020, the rate applicable under section 178 is, subject to paragraph (2), 0.5% per annum.
(2)
Where on a reference date after 14th October 2020 the reference rate found on that date differs from the established rate, the rate applicable under section 178 for the purposes mentioned in paragraph (1) shall, on and after the next operative date, be the higher of–
(a)
0.5% per annum, and
(b)
the percentage per annum found by applying the formula specified in paragraph (3).
(3)
The formula specified in this paragraph is–
where RR is the reference rate referred to in paragraph (2).
3ZE.
(1)
For the purposes of section 68(2) of the Finance Act 2020, the rate applicable under section 178 is, subject to paragraph (2), 0.5% per annum.
(2)
Where, on a reference date after 14th October 2020, the reference rate found on that date differs from the established rate, the rate applicable under section 178 for the purposes mentioned in paragraph (1) shall, on and after the next operative date, be the higher of–
(a)
0.5% per annum, and
(b)
the percentage per annum found by applying the formula specified in paragraph (3).
(3)
The formula specified in this paragraph is–
where RR is the reference rate referred to in paragraph (2).”
The Taxes (Interest Rate) Regulations 1989 specify rates of interest for the purposes of the enactments specified in section 178(2) of the Finance Act 1989.
These Regulations amend the 1989 Regulations to specify the applicable rate of interest for overpayments of digital services tax and for overdue digital services tax. Digital services tax was introduced by Part 2 of the Finance Act 2020.