The Customs and Excise (Personal Reliefs for Special Visitors) Order 1992
S.I. 1992/3156 · Made 10 December 1992 · Extends to United Kingdom
CUSTOMS AND EXCISE
VALUE ADDED TAX
Made 10th December 1992
Laid before the House of Commons 14th December 1992
Coming into force 1st January 1993
The Commissioners of Customs and Excise, in exercise of the powers conferred on them by section 13A of the Customs and Excise Duties (General Reliefs) Act 1979f1 and of all other powers enabling them in that behalf, hereby make the following Order:
Annotations to the whole text
Footnotes
- f1
-
1979 c. 3; section 13A was inserted by section 28 of the Finance Act 1989 (c. 26); section 18(2), as read with section 1(1) of the Customs and Excise Management Act 1979 (c. 2), defines “the Commissioners” as meaning the Commissioners of Customs and Excise.
Contents
- Part I: PRELIMINARY
- 1Article 1
- Part II: INTERPRETATION
- 2Article 2
- Part III: CONDITIONS ATTACHING TO PART VI RELIEFS
- 3Article 3
- 4Article 4
- Part IV: CONDITIONS ATTACHING TO PART VII RELIEFS
- 5Article 5
- 6Article 6
- 7Article 7
- 7AArticle 7A
- 7BArticle 7B
- Part V: CONDITIONS ATTACHING TO ALL RELIEFS
- 8Article 8
- 9Article 9
- 10Article 10
- 11Article 11
- 12Article 12
- 13Article 13
- Part VI: DIPLOMATS ETC
- 14Article 14
- 15Article 15
- 16Article 16
- 17Article 17
- Part VII: VISITING FORCES AND HEADQUARTERS
- 18Article 18
- 19Article 19
- 20Article 20
- 21Article 21
- 22Article 22
- 23Article 23
- Signature
- Schedule Schedule
- Explanatory note
1I1
This Order may be cited as the Customs and Excise (Personal Reliefs for Special Visitors) Order 1992 and shall come into force on 1st January 1993.
2I1
In this Order–
F1“acquisition” means an acquisition of goods from a member State within the meaning given in paragraph 3 of Schedule 9ZA to the Value Added Tax Act 1994 and “acquired” shall be construed accordingly;
“duty” means any duty of customs or duty of excise;
“importation” means an importation from a place outside the F2United Kingdom, and “imported” shall be construed accordingly;
“relief” means the remission of any duty or tax which is chargeable and which a person, whether the person upon whom the relief is conferred or some other person, would be liable to pay were it not for the relief conferred;
“supply” means a supply within the meaning of section 3 of the Value Added Tax Act 1983f1 and “supplied” shall be construed accordingly;
“tax” means value added tax;
“United Kingdom national” means a British citizen, a British Dependent Territories citizen, a British National (Overseas) or a British Overseas citizen;
“used”, in relation to a person’s use of consumable property, includes having theproperty at his disposal;
F3“warehouse” means a warehouse within the meaning of section 1(1) of the Customs and Excise Management Act 1979, any premises in respect of which a person is approved under section 82 of the Finance (No. 2) Act 2023, or premises registered for the safe storage of tobacco products in accordance with regulations made under section 7(1)(b) of the Tobacco Products Duty Act 1979, and “removal from warehouse” is to be construed accordingly.
“removal from warehouse” shall be construed accordingly.
3I1
In this Part–
“entitled person” means an entitled person for the purposes of Part VI.
4I1
It shall be a condition of the relief conferred under article 16 below that the entitled person deliver or cause to be delivered to the supplier of the motor vehicle a certificate in the form numbered 1 in the Schedule to this Order–
containing full information in respect of the matters specified therein; and
signed–
as to Part A, by the entitled person upon whom the relief is conferred;
as to Part B, by the head of the mission or other body or organisation of which the entitled person is a member;
as to Part C, by the Secretary of State or a person authorised to sign on his behalf; and
as to Part D, by the supplier,
before the supply is made.
5I1
In this Part–
“entitled person” means an entitled person for the purposes of Part VII.
For the purposes of articles 6 and 7 below, any reference to a certificate shall be construed as including a reference to a copy of such a certificate.
6I1
It shall be a condition of relief conferred under article 19 below that the entitled person deliver or cause to be delivered in accordance with paragraph (2) below five certificates in the form numbered 2 in the Schedule to this Order–
containing full information in respect of the matters specified therein; and
signed–
as to Part A, by the entitled person upon whom the relief is conferred; and
as to Part B, by the officer commanding the visiting force or other body or organisation of which the entitled person is a member or by a person authorised to sign on his behalf.
The certificates referred to in paragraph (1) above shall be delivered before the supply is made as follows:
two certificates shall be delivered to the visiting force or other body or organisation of which the entitled person is a member;
two certificates shall be delivered to the proper officer; and
one certificate shall be delivered to the supplier of the motor vehicle.
7I1
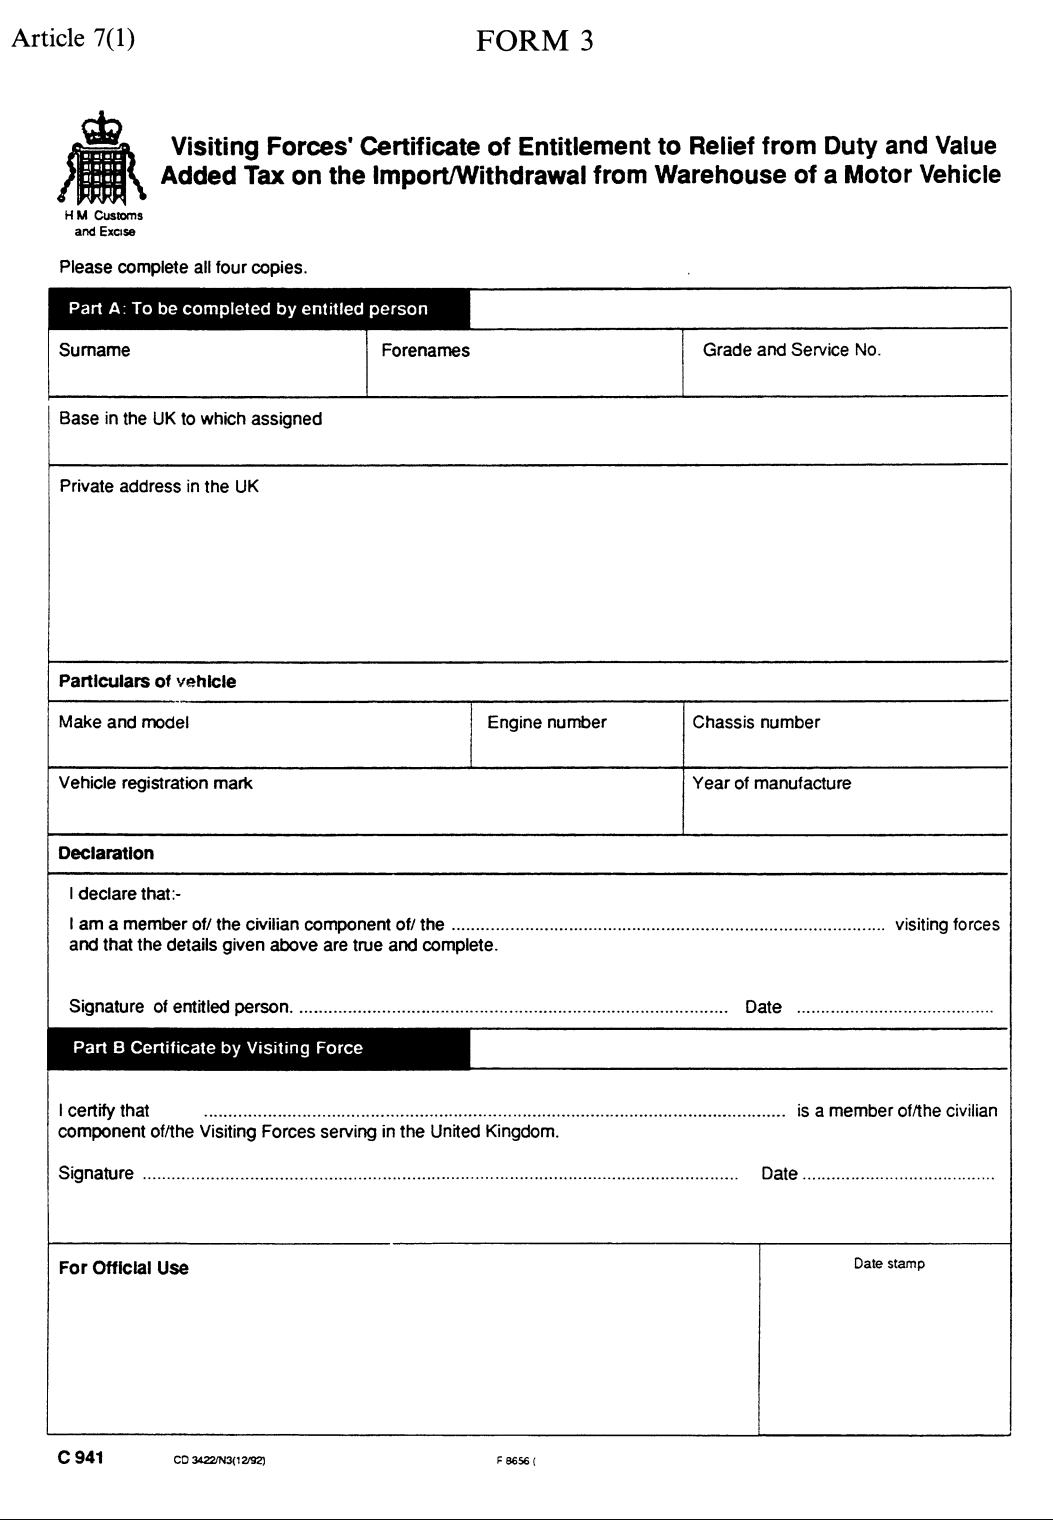
It shall be a condition of relief conferred under article 20 below in respect of a motor vehicle that the entitled person deliver or cause to be delivered in accordance with paragraph (2) below four certificates in the form numbered 3 in the Schedule to this Order–
containing full information in respect of the matters specified therein; and
signed–
as to Part A, by the entitled person upon whom the relief is conferred; and
as to Part B, by the officer commanding the visiting force or other body or organisation of which the entitled person is a member or by a person authorised to sign on his behalf.
The certificates referred to in paragraph (1) above shall be delivered before the goods are removed by or on behalf of the entitled person as follows:
one certificate shall be delivered to the visiting force or other body or organisation of which the entitled person is a member; and
three certificates shall be delivered to the proper officer.
7AF1
Nothing in this Order affords any relief from VAT charged under paragraph 3(2) of Schedule 9ZB to the Value Added Tax Act 1994.
7BF1
Article 21 applies in respect of tax where a gift of goods, other than tobacco products or beverages containing alcohol, is made to an entitled person by dispatching them to that person in Northern Ireland from Great Britain or the Isle of Man, as it applies where a gift of goods is made to an entitled person by dispatching them to the person from a place outside the United Kingdom.
8I1
In this Part–
“entitled person” means an entitled person for the purposes of either part VI or Part VII of this Order.
9I1
An entitled person upon whom any relief is conferred under any Part of this Order shall be bound by the conditions described in the following provisions of this Part and in Part III or IV above, as the case may be.
10I1
It shall be a condition of the relief that the goods shall not be lent, hired-out, given as security or transferred by the entitled person or any other person without the prior authorisation in writing of the Commissioners.
Where the Commissioners authorise such disposal as is mentioned in paragraph (1) above, they may discharge the relief and the entitled person to whom the relief was afforded shall forthwith pay the duty or tax at the rate then in force, provided that where a lower rate was in force when relief was afforded the amount payable shall be determined by reference to the lower rate.
11I1
It shall be a condition of the relief that the goods are used exclusively by the entitled person or members of his family forming part of his household.
12I1
Where relief has been afforded and subsequently the Commissioners are not satisfied that any condition attaching to such relief, whether by virtue of a provision of this Order or otherwise, has been complied with, then, unless the Commissioners sanction the non-compliance in writing, the duty or tax shall become payable forthwith and the goods shall be liable to forfeiture.
13I1
Where relief has been afforded, but any duty or tax subsequently becomes payable by virtue or article 12 above, the following persons shall be jointly and severally liable to pay it–
the entitled person upon whom the relief was conferred;
any person who, at or after the time of the non-compliance with the condition which has caused the duty or tax to become payable, has been in possession of the goods.
14F1
In this Part–
“entitled person” means any person who is neither a United Kingdom national nor a permanent resident of the United Kingdom and:
- (a)
who enjoys any privilege or immunity by virtue of that person being –
- (i)
a diplomatic agent for the purposes of the Diplomatic Privileges Act 1964,
- (ii)
a senior officer of the Commonwealth Secretariat for the purposes of the Commonwealth Secretariat Act 1966,
- (iii)
a consular officer for the purposes of the Consular Relations Act 1968,
- (iv)
a representative or a person recognised as holding a rank equivalent to a diplomatic agent for the purposes of the International Organisations Act 1968, or
- (i)
- (b)
whose circumstances, at the time the duty or tax in respect of which relief is sought would otherwise become due, are such that had those circumstances existed immediately before exit day, that person would have enjoyed, under or by virtue of section 2 of the European Communities Act 1972, any privilege or immunity similar to those enjoyed under or by virtue of the enactments specified in paragraph (a) above by the persons therein specified.
15I1
Where any tobacco product or beverage containing alcohol is removed from warehouse in the course of its being supplied to an entitled person, payment of any duty or tax chargeable in respect of the removal from warehouse or supply shall not be required.
16I1
Subject to the following provisions of this article, where an entitled person purchases a motor vehicle which has been manufactured in a country F1... which is–
a member State; or
a member of the European Free Trade Association,
payment of any tax chargeable in respect of the supply shall not be required.
No relief shall be afforded under paragraph (1) above if the entitled person has previously been afforded relief in respect of any other motor vehicle, whether under paragraph (1) above or otherwise, unless he has disposed of all previous motor vehicles in respect of which relief has been so afforded and paid any duty or tax which was required to be paid under article 10(2) above.
Where the spouse F2or civil partner of the entitled person is present in the United Kingdom, paragraph (2) above shall apply as if the words “(or all but one)” were inserted after the words “motor vehicles”.
17I1
Nothing in this Part of this Order shall be taken as conferring relief in respect of any duty or tax which is subject to remission or refund by or under any of the enactments referred to in article 14 above.
18I1
In this Part–
“entitled person” means a person who is–
- (a)
F1for the purposes of any provision of the Visiting Forces Act 1952, a serving member of a visiting force—
- (i)
of a country, other than the United Kingdom, which is a party to the North Atlantic Treaty, or
- (ii)
of a member State of the European Union stationed in Northern Ireland to take part in a defence effort carried out under the common security and defence policy established under Article 42(1) of the Treaty on European Union (provisions on the common security and defence policy),
or a person recognised by the Secretary of State as a member of a civilian component of such a force, or
- (i)
- (b)
a person who is a military or civilian member of a headquarters or organisation designated for the purposes of any provision of the International Headquarters and Defence Organisations Act 1964f1,
who is neither a United Kingdom national nor a permanent resident of the United Kingdom.
- (a)
19I1
Subject to article 22 below, where an entitled person purchases a motor vehicle which has been manufactured in a country which is–
a member State; or
a member of the European Free Trade Association,
payment of any tax in respect of the supply shall not be required.
20I1
Subject to F1articles 22 and 23 below, where an entitled person imports, acquires or removes from warehouse any goods, payment of any duty or tax chargeable in respect of the importation, acquisition or removal from warehouse shall not be required.
21I1
Subject to F1articles 22 and 23 below, where a gift of goods, other than tobacco products or beverages containing alcohol, is made to an entitled person by dispatching them to him from a place outside the United Kingdom, payment of any duty or tax chargeable in respect of their acquisition or importation shall not be required.
22I1
No relief shall be afforded under this Part of this Order in respect of a motor vehicle if the entitled person has previously been afforded relief under this Order in respect of any other motor vehicle, unless he has disposed of all previous motor vehicles in respect of which relief has been so afforded and paid any duty or tax which was required to be paid under article 10(2) above.
Where the spouse F1or civil partner of the entitled person is present in the United Kingdom, paragraph (1) above shall apply as if the words “(or all but one)” were inserted after the words “motor vehicles”.
23F1
Relief under articles 20 and 21 does not extend to payment of any duty of customs in respect of a person who is an entitled person in relation to a visiting force referred to in article 18(a)(ii).
Signature
Leonard Harris
Commissioner of Customs and Excise
New King’s Beam House,
22 Upper Ground,
London,
SE1 9PJ
I1


Explanatory note
(This note is not part of the Order)
This Order brings into force on 1st January 1993 certain reliefs for diplomats, members of international organisations and visiting forces and other persons which are currently allowed by extra-statutory concession. It also incorporates certain statutory reliefs for visiting forces which have been provided by Part XIII of the Customs and Excise (Personal Reliefs for Goods Permanently Imported) Order 1983, and which are to be revoked by a 1992 Order of the same title. The Order implements Articles 14(1)(g), 15(10) and 28cB of Council Directive 77/388/EEC (OJ L145, 13.6.77, p.1), as amended by Council Directive 91/680/EEC (OJ L376, 31.12.91, p.1).
Part III of the Order provides for the completion of a certain form as a condition of the relief on the purchase by diplomats etc of cars manufactured within another member State of the European Community or within a country which is a member of the European Free Trade Association.
Part IV lays down similar requirements in relation to the reliefs on cars purchased or imported by members of visiting forces.
Part V imposes a number of conditions to which all the reliefs are subject.
Part VI sets out the reliefs to which certain diplomats and persons of similar status are entitled.
Part VII sets out the reliefs to which members of NATO visiting forces and headquarters organisations are entitled.