Finance Act 1966
1966 c. 18 · Enacted 3 August 1966 · Extends to United Kingdom
An Act to grant certain duties, to alter other duties, and to amend the law relating to the National Debt and the Public Revenue, and to make further provision in connection with Finance.
Annotations to the whole text
Modifications
- C1
Words of enactment omitted under authority of Statute Law Revision Act 1948 (c. 62), s. 3
- C2
General amendments to Tax Acts made by Taxes Management Act 1970 (c. 9, SIF 63:1), s. 41A(7) (as added by Finance Act 1990 (c. 29, SIF 63:1), s. 95(1)(2)), British Telecommunications Act 1981 (c. 38, SIF 96), s. 82(2)(7); Telecommunications Act 1984 (c. 12, SIF 96), s. 72(3); Finance Act 1984 (c. 43, SIF 63:1), ss. 82(6), 85(2), 89(1)(7), 96(1)(7), 98(7), Sch. 9 para. 3(2)(9), Sch. 16 paras. 6, 12 and Finance Act 1985 (c. 54, SIF 63:1), ss. 72(1), 74(5), Sch. 23 para. 15(4), S.I. 1987/530, regs. 11(2), 13(1), 14, Income and Corporation Taxes Act 1988 (c. 1, SIF 63:1), ss. 4, 6, 7, 9, 32, 34, 78, 134, 135, 141, 142, 185, 191, 193, 194, 195, 200, 203, 209, 212, 213, 219, 247, 253, 272, 287, 314, 315, 317, 318, 325, 326, 327, 345, 350, 351, 368, 375, 381, 397, 414, 432, 440, 442, 446, 458, 460, 461, 463, 463(2)(3) (as added by Finance Act 1990 (c. 29, SIF 63:1), s. 50(2) ), 468, 474, 475, 486, 490, 491, 503, 511, 518, 524, 532, 544, 550, 556, 558, 569, 572, 582, 595, 601, 613, 617, 619, 621, 639, 656, 660, 663, 676, 689, 691, 694, 700, 701, 714, 716, 739, 743, 754, 763, 776, 780, 781, 782, 787, 789, 811, 828, 829, 832, 833, 834, 835, 837, 838, 839, 840, 841, 842, Sch. 2 para. 5, Sch. 4 para. 5, Sch. 13 para. 10, Sch. 16 para. 10, Sch. 21 para. 6, Sch. 26 para. 1, Sch. 27 para. 20, Finance Act 1988 (c. 39, SIF 63:1), ss. 66, 127(1)(6), Sch. 12 para. 6, Capital Allowances Act 1990 (c. 1, SIF 63:1), ss. 28(1), 68(8), 74, 82, 83(5), 148(5), 163(4), 164(2), S.I. 1990/627 and Finance Act 1990 (c. 29, SIF 63:1), s. 25(10)
Commencement
- I1
Act partly in force at Royal Assent, partly prospective, see individual sections; all provisions so far as unrepealed wholly in force at 1.2.1991
Extent
- E1
For the extent of this Act see s. 53(4)(5)
Editorial notes
- X1
The text of Ss. 12(6)(b), 15(5), Sch. 3, para. 6 was taken from S.I.F. Group 12:1 (Betting, Gaming and Lotteries: General), Ss. 2, 53(1)-(4) from S.I.F. Group 40:1 (Customs and Excise: General), ( Ss. 27, Sch.5, para. 19, Sch. 6, paras. 14, 23, Sch. 13 from S.I.F Group 63:1 (Income, Corporation & Capital Gains Taxes: Income and Corporation Taxes) and Ss. 45-47 from S.I.F. Group 114 (Stamp Duty) ; provisions omitted from S.I.F. have been dealt with as referred to in other commentary.
- X2
General amendments to Tax Acts, Income Tax Acts, and/or Corporation Tax Acts made by legislation after 1.2.1991 are noted against Income and Corporation Taxes Act 1988 (c. 1, SIF 63:1) but not against each Act
Contents
- Part I: Customs and Excise
- 1. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 2Reliefs for shipbuilders in respect of certain duties. Repealed
- 3. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 4, 5. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 6. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 7. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 8. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 9. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 10, 11. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- Duties relating to betting and gaming
- 12General Betting Duty.
- 13. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 14. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- Duties relating to betting and gaming
- 15Additional or supplementary provisions as to duties on betting or gaming.
- 16. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- Part II
- 17—25. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- Part III: CORPORATION TAX ACTS
- 26. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 27Amendments of Corporation Tax Acts. Repealed
- 28. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 29. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 31, 32. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 33, 34. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- Part IV
- 35—39. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 40. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- Part V
- 41, 42. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 43. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- Part VI
- 44. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- Part VII: Miscellaneous
- 45Harbour reorganisation schemes: corporation tax and stamp duty. Repealed
- 46. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 47. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 48. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 49—51. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 52. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . Repealed
- 53Short title, construction, extent and repeals.
- Schedule 1: Reliefs For Shipbuilders
- Part I: Determination of Open Market Value
- 1Paragraph 1
- Part II: Reductions in Purchase Price or Open Market Value
- 2Paragraph 2
- 3Paragraph 3
- Part III: Supplemental
- 4Paragraph 4
- 5Paragraph 5
- 6Paragraph 6
- 7Paragraph 7
- Schedule 2.. . . . . . . . . . . . . . . . . . . . . . . . Schedule 2.. . . . . . . . . . . . . . . . . . . . . . . .
- Schedule 3: Supplementary Provisions as to Duties relating to Betting and Gaming
- Part I: Duties relating to Betting
- 1—5Paragraph 1—5 Repealed
- 6Paragraph 6 Repealed
- 7—26Paragraph 7—26 Repealed
- Schedule 4.. . . . . . . . . . . . . . . . . . . . . . . . Schedule 4.. . . . . . . . . . . . . . . . . . . . . . . .
- Schedule 5: Amendments of Corporation Tax Acts
- 1—18Paragraph 1—18 Repealed
- Transitional relief for company with overseas trading income which is a member of a group
- 19Paragraph 19 Repealed
- 20Paragraph 20 Repealed
- Schedule 6: Administration of Corporation Tax Acts
- 1—13Paragraph 1—13 Repealed
- Priority of corporation tax and other tax in liquidation Repealed
- 14Paragraph 14 Repealed
- 15—22Paragraph 15—22 Repealed
- Transitional relief for existing companies with overseas trading income Repealed
- 23Paragraph 23 Repealed
- 24—27Paragraph 24—27 Repealed
- Schedule 7.. . . . . . . . . . . . . . . . . . . . . . . . Schedule 7.. . . . . . . . . . . . . . . . . . . . . . . .
- Schedule 8.. . . . . . . . . . . . . . . . . . . . . . . . Schedule 8.. . . . . . . . . . . . . . . . . . . . . . . .
- Schedule 9.. . . . . . . . . . . . . . . . . . . . . . . . Schedule 9.. . . . . . . . . . . . . . . . . . . . . . . .
- Schedule 10. . . . . . . . . . . . . . . . . . . . . . . . Schedule 10. . . . . . . . . . . . . . . . . . . . . . . .
- Schedule 11.. . . . . . . . . . . . . . . . . . . . . . . .Schedule 11.. . . . . . . . . . . . . . . . . . . . . . . .
- Schedule 12.. . . . . . . . . . . . . . . . . . . . . . . .Schedule 12.. . . . . . . . . . . . . . . . . . . . . . . .
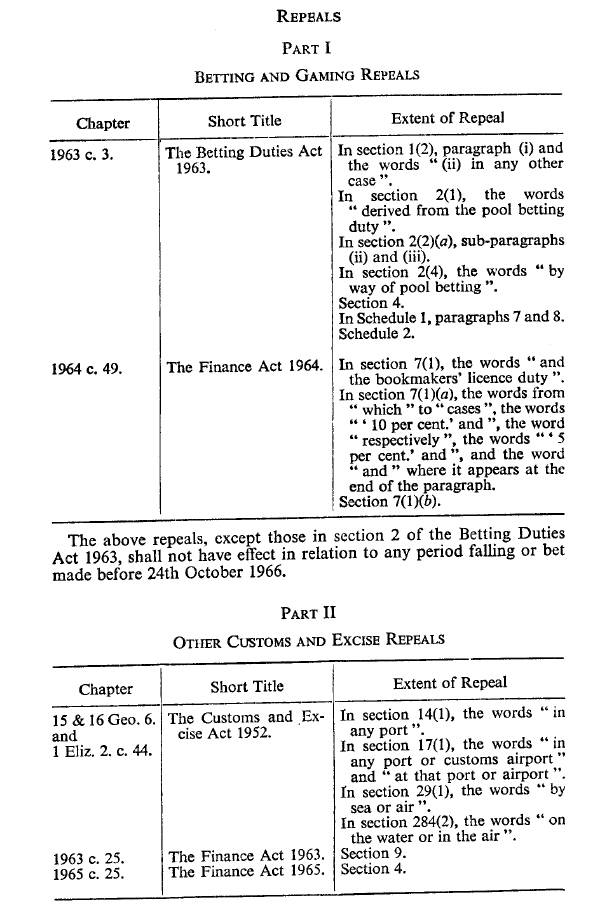
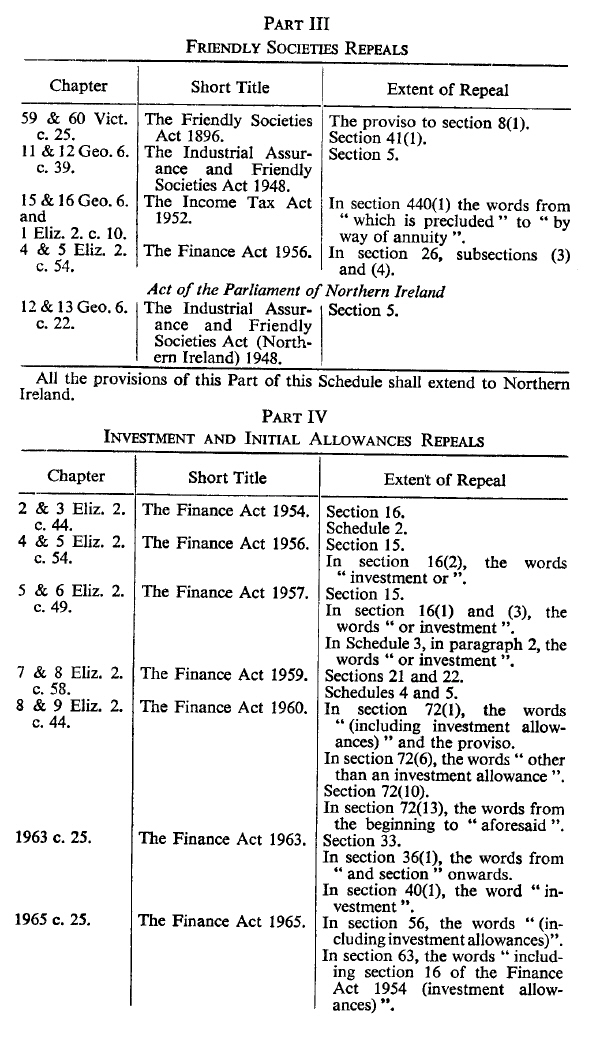
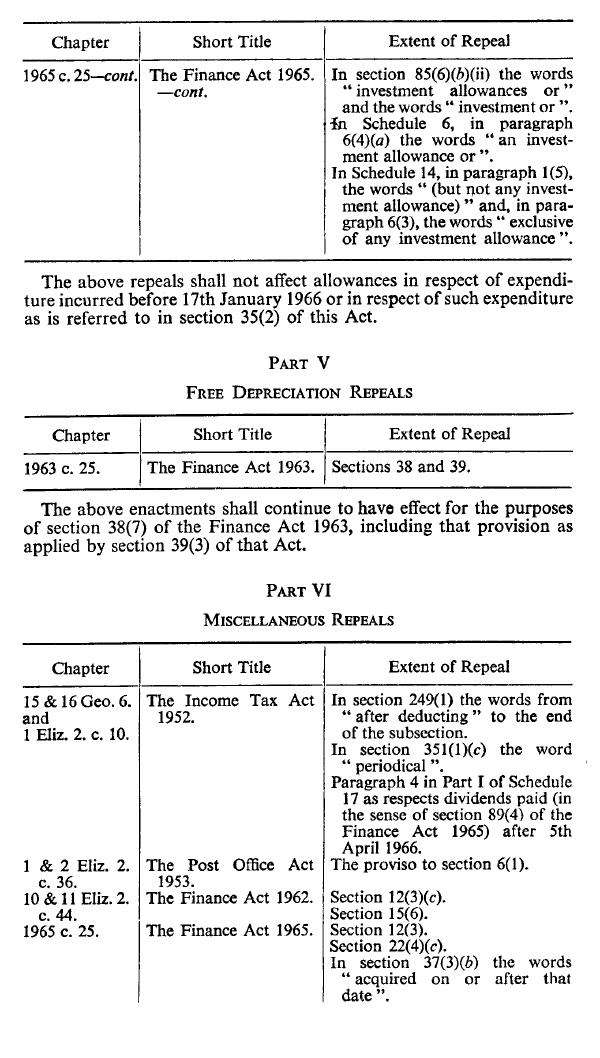
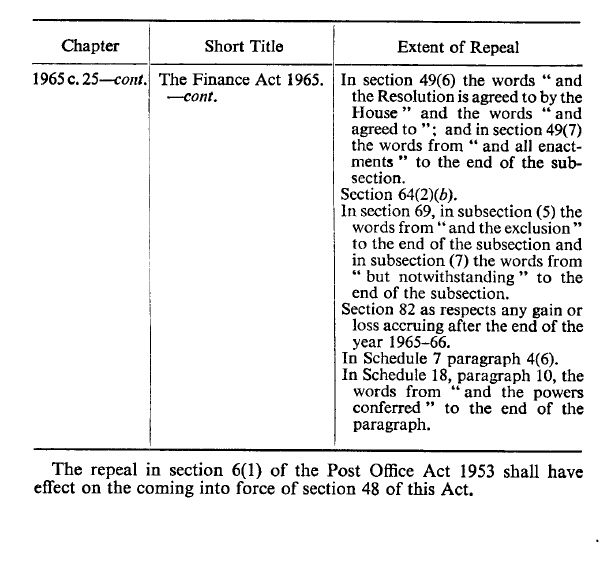
- Schedule 13REPEALS
1. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
2Reliefs for shipbuilders in respect of certain duties.F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
3. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
4, 5. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
6. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
7. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
8. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
9. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
10, 11. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
12General Betting Duty.C1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . F1
The pool betting duty shall not be chargeable on any bet made as mentioned in subsection (1)(c) of this section on or after 24th October 1966, and accordingly from that date—
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
paragraph 4(a)(i) of Schedule 5 to the M1Betting, Gaming and Lotteries Act 1963 (which relates to the disposal of amounts staked by means of a totalisator on a dog racecourse) for the words “pool betting duty” there shall be substituted the words “general betting duty” ;
and as from that date bookmakers’ licence duty shall cease to be charged.
13. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
14. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
15Additional or supplementary provisions as to duties on betting or gaming.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . F1
The supplemental provisions set out in Schedule 3 to this Act shall have effect with respect to the duties relating to betting and gaming.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
16. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
17—25. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
26. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
27Amendments of Corporation Tax Acts.F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
28. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
29. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
31, 32. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
33, 34. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
35—39. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
40. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
41, 42. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
43. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
44. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
45Harbour reorganisation schemes: corporation tax and stamp duty.F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
46. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
47. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
48. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
49—51. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
52. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F1
53Short title, construction, extent and repeals.
This Act may be cited as the Finance Act 1966.
Any reference in this Act to any other enactment shall, except so far as the context otherwise requires, be construed as a reference to that enactment as amended or applied by or under any other enactment, including this Act.
Except as otherwise expressly provided, such of the provisions of this Act as relate to matters in respect of which the Parliament of Northern Ireland has power to make laws shall not extend to Northern Ireland.
This Act, in so far as it affects the operation of the Sugar Act 1956, shall extend to the Isle of Man.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . F4
The enactments mentioned in Schedule 13 to this Act are hereby repealed to the extent mentioned in the third column of that Schedule, but subject to any provision in relation thereto made at the end of any Part of that Schedule.
1
The open market value of any vessel or other structure and its fittings and equipment shall be taken for the purposes of section 2 of this Act to be the price which they would fetch at the time of their delivery pursuant to the contract in question on a sale in the open market between buyer and seller independent of each other.
The said price shall be determined on the assumption that the buyer will bear freight, insurance and all other costs, charges and expenses incurred in respect of the vessel or structure and other items in question after their delivery as aforesaid or, where delivery is to be effected outside the United Kingdom, after their departure from the United Kingdom for the purpose.
For the purposes of this paragraph, a sale in the open market between a buyer and seller independent of each other presupposes—
that the vessel or structure and other items in question are the sole consideration for the price paid, and
that the price is not influenced by any commercial, financial or other relationship, whether by contract or otherwise, between the seller or any person associated in business with him and the buyer or any person associated in business with him (other than the relationship created by the sale of the said vessel or structure and other items), and
that neither the seller nor any person associated in business with him has provided any part of the price, and that no part of the price will be returned to the buyer or any person associated in business with him.
For the purposes of the last foregoing sub-paragraph, two persons shall be deemed to be associated in business with one another if, whether directly or indirectly, either of them has any interest in the business or property of the other, or both have a common interest in any business or property, or some third person has an interest in the business or property of both of them.
2
Where the amount payable in respect of any vessel or other structure under the said section 2 is, by virtue of subsection (3) thereof, to be determined by reference to the price payable as mentioned in that subsection, then—
if the terms of the contract in question are such that the applicant for the payment will bear any of the following, that is, any freight, insurance or other costs, charges or expenses incurred in respect of the vessel or structure or its fittings or equipment after their delivery pursuant thereto or, where delivery is to be effected outside the United Kingdom, after their departure from the United Kingdom for the purpose, the price shall be treated for the purposes of that subsection as reduced by an amount reflecting the burden thus assumed by the applicant;
if the whole or any part of the price is payable twelve months or more after the time when the property in the vessel or structure passes or, if later, the time of delivery of the vessel or structure or of its departure from the United Kingdom for the purpose of delivery, the price shall be treated for those purposes as reduced by an amount representing the discount which would be chargeable for obtaining payment at that earlier time at a rate of interest equal to the bank rate then prevailing.
In the foregoing sub-paragraph “bank rate” means the minimum rate at which the Bank of England will lend to a discount house having access to the Discount Office of the Bank.
3C1
If, after consultation with the Board of Trade, it appears to the Commissioners that the fittings and other equipment supplied with any vessel or other structure include any items the supply of which would not in the ordinary course of events be undertaken by a person building such a vessel or structure for delivery to another as that other’s property, the price or, as the case may be, open market value referred to in the said subsection (3) shall be treated for the purposes of that subsection as reduced by an amount equal to the open market value of the items in question; and the provisions of paragraph 1 of this Schedule shall apply for the purpose of determining that value, subject to any necessary modifications.
4
The following provisions of the F1M1Customs and Excise Management Act 1979 shall apply in relation to payments under the said section 2 as they apply in relation to drawbacks, allowances or repayments under the Customs and Excise Acts 1979, that is to say, section 135 (time limit on payment), section 136(1) and (2) (offences in connection with claims) and section 167(4) (recovery of overpayments).
5
Any officer or person authorised by the Commissioners may require any person who has been concerned at any stage with a vessel or other structure in respect of which an application has been made under the said section 2, or with any fittings or other equipment supplied therewith, or with any payment in respect of the vessel or structure or any fittings or other equipment so supplied—
to furnish, within such time as that officer or person may require, such information as may be reasonably necessary to enable the Commissioners to determine whether the applicant is entitled to a payment under that section, or liable to make any repayment thereunder, or to determine the amount of any payment to which the applicant is so entitled, and
to produce for inspection by that officer or person, at such time and place as he may require, any books or accounts or other document of whatever nature relating to, or to any payment in respect of, the said vessel, structure, fittings or equipment.
Any such officer or person shall be entitled to take extracts from or make copies of any document produced to him under the foregoing sub-paragraph.
If any person fails to comply with any requirement under sub-paragraph (1) above, he shall be liable to a penalty of F1level 3 on the standard scale, together with a further penalty of ten pounds for each day during which failure to comply with the requirement continues.
6
Any dispute as to the determination for the purposes of an application under the said section 2 of the price or value referred to in subsection (3) of that section, or of any amount by which that price or value is to be treated as reduced by virtue of subsection (4) thereof, shall be referred to a referee appointed in accordance with the next following sub-paragraph.
A reference under the foregoing sub-paragraph shall be to a person (not being an official of any government department) appointed by the Lord Chancellor F1with the concurrence of the Lord Chief Justice of England and Wales or, if the application for the purposes of which the determination is made relates to a vessel or structure constructed in Scotland or Northern Ireland, or was by a company incorporated in Scotland or Northern Ireland, and the applicant in either case so requires, appointed by the Lord President of the Court of Session or as the case may be, F2by the Lord Chancellor with the concurrence of the Lord Chief Justice of Northern Ireland.
The procedure on any such reference shall be such as the referee may determine.
Sub-paragraph (1) above shall not have effect, and any price, value or amount falling to be determined for the purposes of the said subsection (3) or (4) shall be that fixed by the Commissioners, unless, within three months from the time when the Commissioners’ final determination thereof is communicated to him, or such longer time as the Commissioners may allow, a notice requiring a reference under that sub-paragraph has been served on the Commissioners by the person for the purposes of whose application the determination was made.
The Lord Chief Justice of England and Wales may nominate a judicial office holder (as defined in section 109(4) of the Constitutional Reform Act 2005) to exercise his functions under this paragraph.
The Lord Chief Justice of Northern Ireland may nominate any of the following to exercise his functions under sub-paragraph (2)—
the holder of one of the offices listed in Schedule 1 to the Justice (Northern Ireland) Act 2002;
a Lord Justice of Appeal (as defined in section 88 of that Act).
7
The making by the Commissioners of a payment under the said section 2 determined by reference to the price or value referred to in subsection (3) of that section, or that price or value as reduced by virtue of subsection (4) thereof, shall not be taken as constituting the making by the Commissioners of a final decision under the said subsection (3).
Schedule 2.. . . . . . . . . . . . . . . . . . . . . . . . F1
1—5
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . F1
6F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
7—26
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . F1
Schedule 4.. . . . . . . . . . . . . . . . . . . . . . . . F1
1—18
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . F1
19F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
20
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . F1
1—13F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
14F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
15—22F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
23F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
24—27F1
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Schedule 7.. . . . . . . . . . . . . . . . . . . . . . . . F1
Schedule 8.. . . . . . . . . . . . . . . . . . . . . . . . F1
Schedule 9.. . . . . . . . . . . . . . . . . . . . . . . . F1
Schedule 10. . . . . . . . . . . . . . . . . . . . . . . . F1
Schedule 11.. . . . . . . . . . . . . . . . . . . . . . . .F1
Schedule 12.. . . . . . . . . . . . . . . . . . . . . . . .F1
Schedule 13REPEALSC1