The Stamp Duty Land Tax (Administration) (Amendment) Regulations 2011
S.I. 2011/455 · Made 22 February 2011
Stamp Duty Land Tax
Made 22nd February 2011
Laid before the House of Commons 22nd February 2011
Coming into force 1st April 2011
The Commissioners for Her Majesty’s Revenue and Customs, in exercise of the powers conferred by sections 113(2) and 114(6) of, and paragraph 1 of Schedule 10 to the Finance Act 2003f1, make the following Regulations:
Annotations to the whole text
Footnotes
- f1
-
2003 c. 14. Section 114(6) was inserted by section 19(2) of the Finance Act 2007 (c. 11). The functions of the Commissioners of Inland Revenue were transferred to the Commissioners for Her Majesty’s Revenue and Customs by section 5(2) of the Commissioners for Revenue and Customs Act 2005 (c.11). Section 50(1) of that Act provides that insofar as it is appropriate in consequence of section 5, a reference to the Commissioners of Inland Revenue shall be taken as a reference to the Commissioners for Her Majesty’s Revenue and Customs.
Contents
- 1Citation, commencement and interpretation
- 2Amendment of the Principal Regulations
- 3Transitional Provisions
- Signature
- Schedule 1
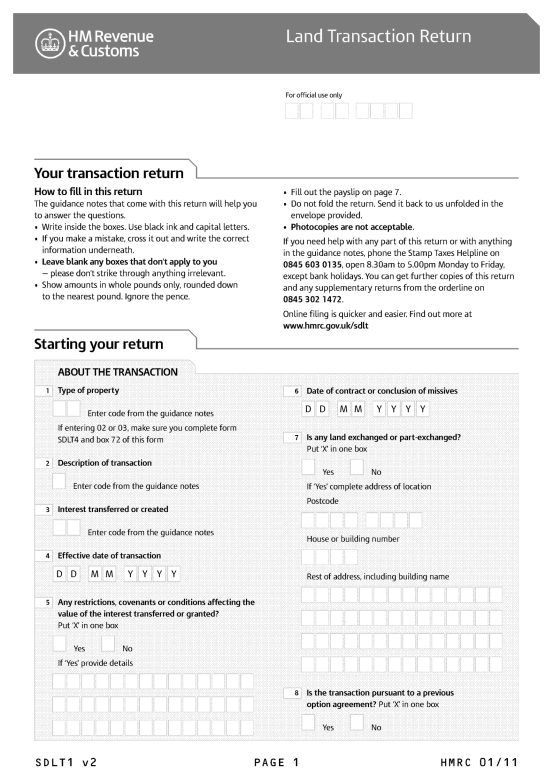
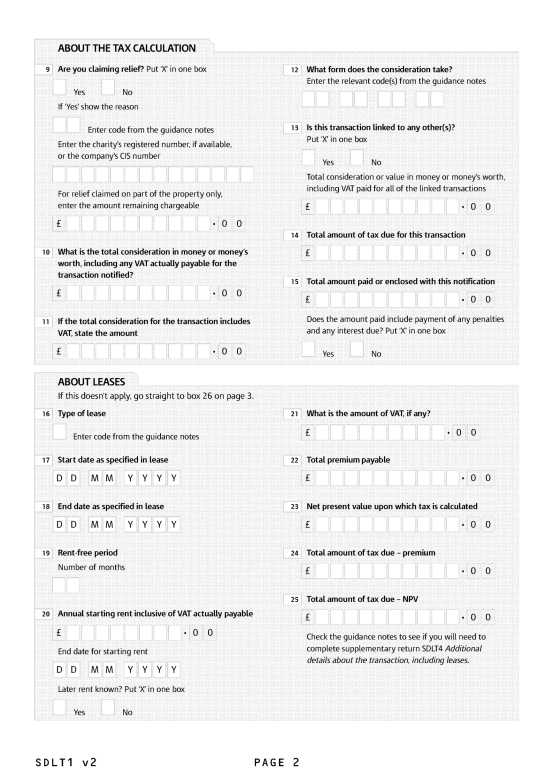
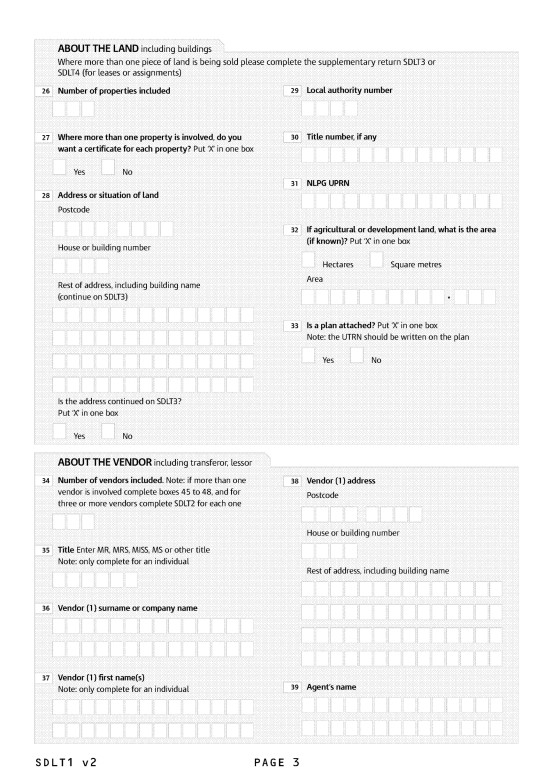
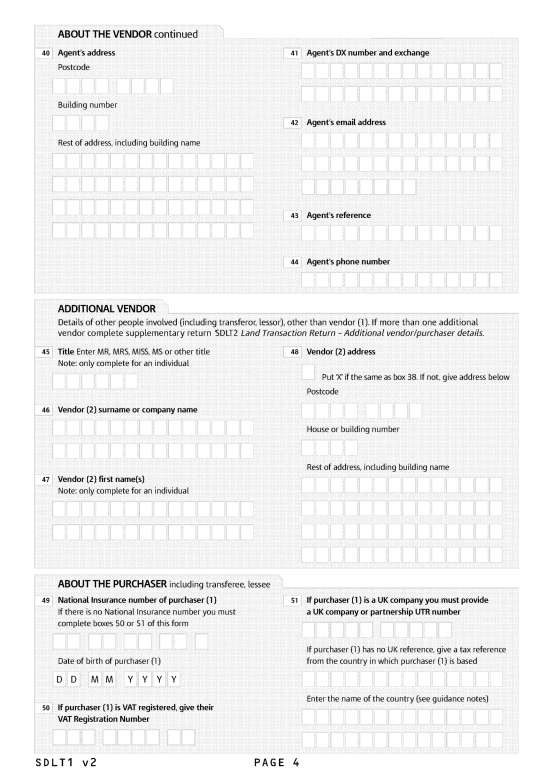
- 1LAND TRANSACTION RETURN
- 2ADDITIONAL DETAILS ABOUT THE LAND
- 3ADDITIONAL DETAILS ABOUT THE TRANSACTION, INCLUDING LEASES
- Explanatory note
1Citation, commencement and interpretation
These Regulations may be cited as the Stamp Duty Land Tax (Administration) (Amendment) Regulations 2011 and come into force on 1st April 2011.
In these Regulations—
-
“formerly prescribed form” means the form previously prescribed in the respective Part of Schedule 2 to the Principal Regulations immediately before the coming into force of these Regulations;
-
“substituted form” means the form substituted in the respective Part of Schedule 2 to the Principal Regulations by virtue of the amendments made by these Regulations;
-
“the Principal Regulations” means the Stamp Duty Land Tax (Administration) Regulations 2003f1.
2Amendment of the Principal Regulations
The Principal Regulations are amended as follows.
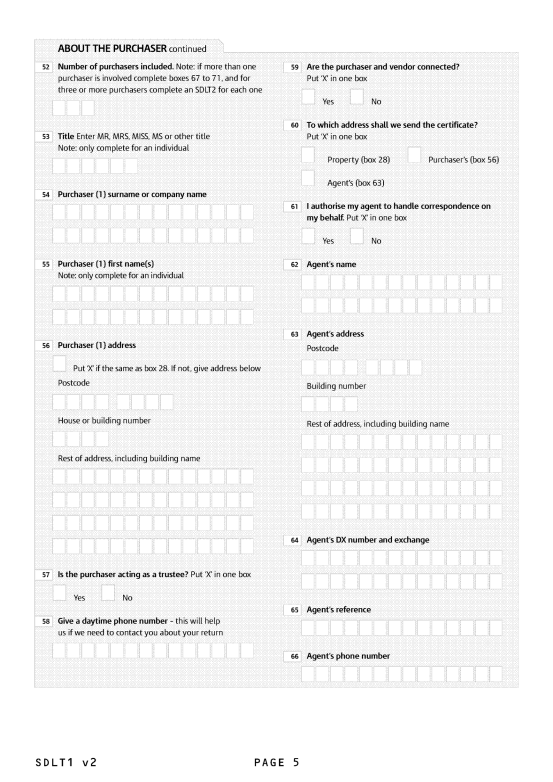
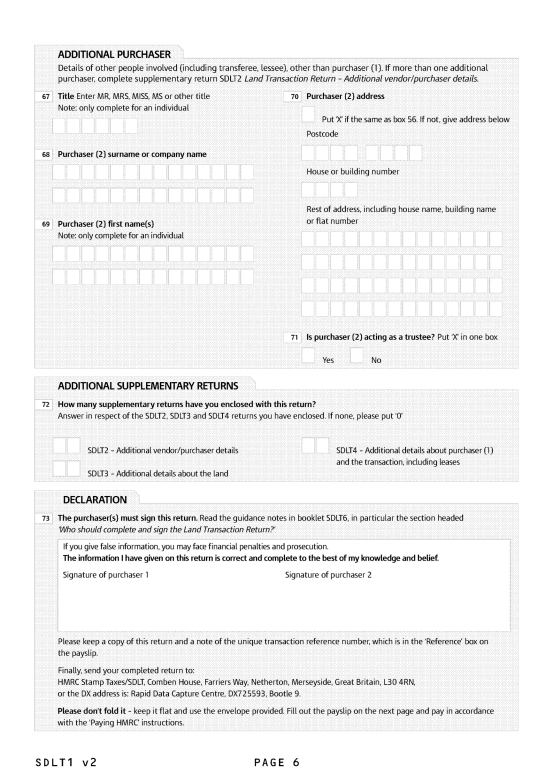
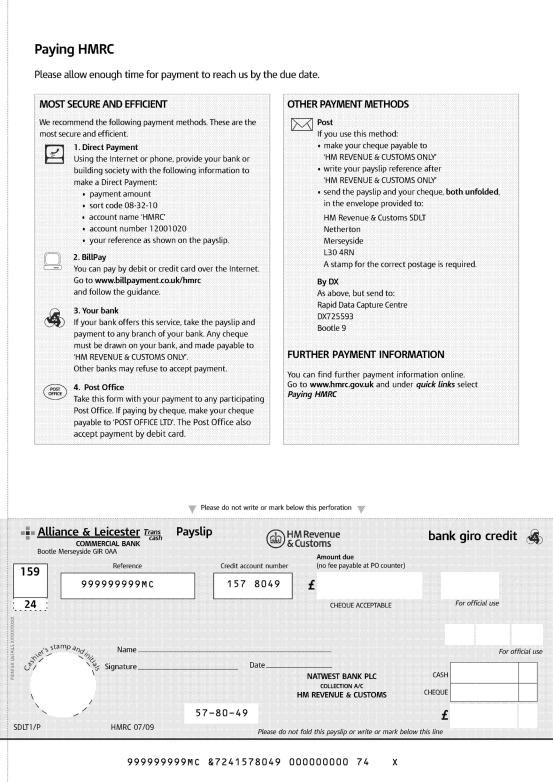
For the form in Part 1 of Schedule 2 to the Principal Regulations (which sets out the main form of a land transaction return) substitute the form set out in Part 1 of the Schedule to these Regulations.
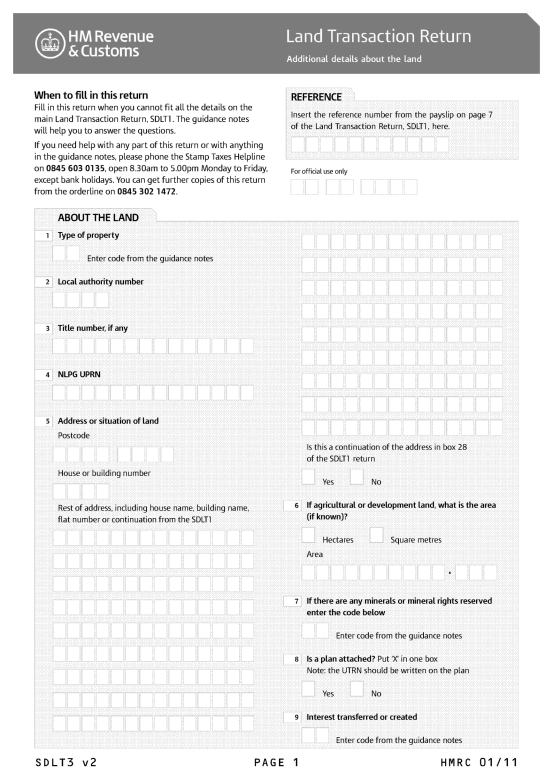
For the form in Part 3 of Schedule 2 to the Principal Regulations (which sets out the form of a land transaction return requiring additional details about the land) substitute the form set out in Part 2 of the Schedule to these Regulations.
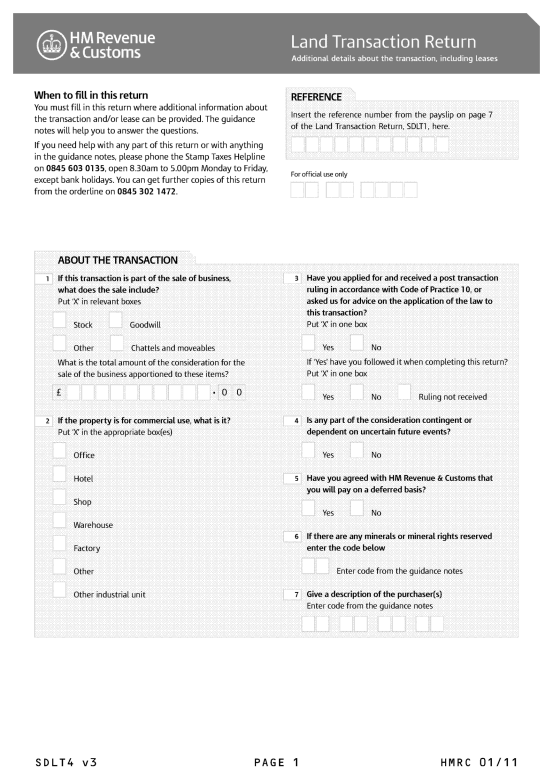
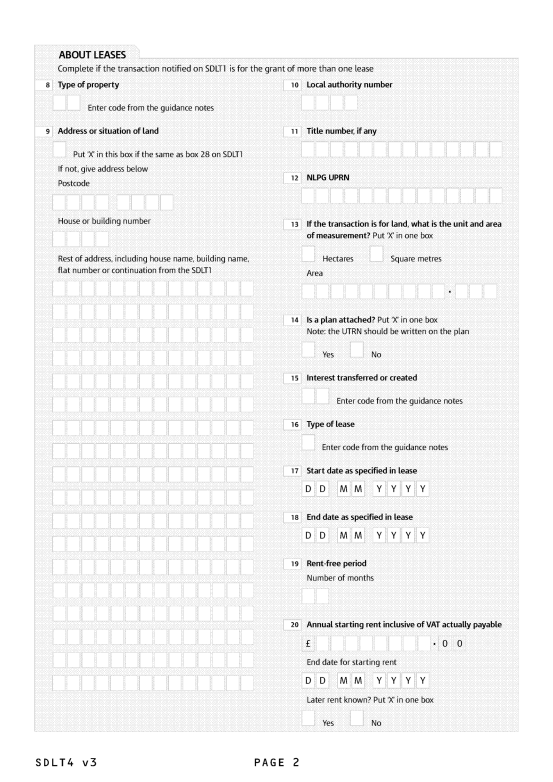
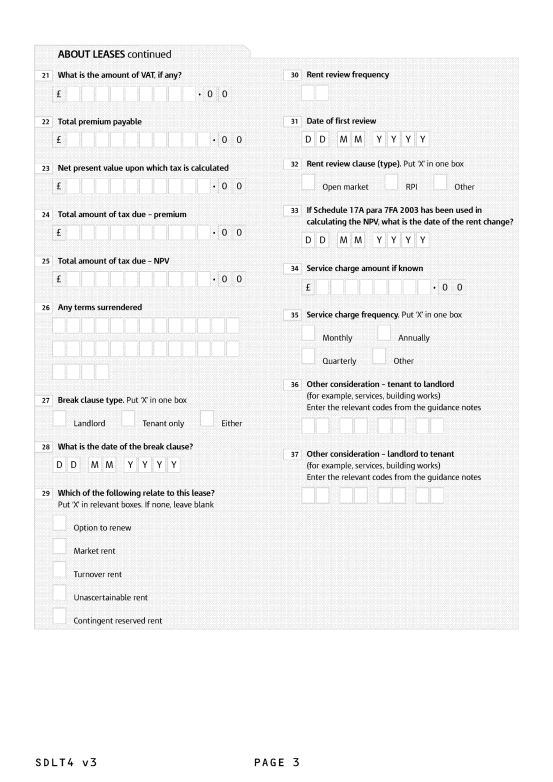
For the form in Part 4 of Schedule 2 to the Principal Regulations (which sets out the form of a land transaction return requiring additional details about the transaction, including leases) substitute the form set out in Part 3 of the Schedule to these Regulations.
3Transitional Provisions
In relation to forms delivered before 4th July 2011—
the requirement to deliver a land transaction return in the form prescribed by Part 1 of Schedule 2 to the Principal Regulations containing the information required by that form, is satisfied by delivering a return—
on the substituted form in Part 1, containing the information required by that form, or
on the formerly prescribed form in Part 1, containing the information required by that form.
the requirement to deliver a land transaction return in the form prescribed by Part 3 of Schedule 2 to the Principal Regulations containing the information required by that form, is satisfied by delivering a return—
on the substituted form in Part 3, containing the information required by that form, or
on the formerly prescribed form in Part 3, containing the information required by that form.
the requirement to deliver a land transaction return in the form prescribed by Part 4 of Schedule 2 to the Principal Regulations containing the information required by that form is satisfied by delivering a return—
on the substituted form in Part 4, containing the information required by that form, or
on the formerly prescribed form in Part 4, containing the information required by that form.
Signature
Dave Hartnett
Steve Lamey
Two of the Commissioners for Her Majesty’s Revenue and Customs
22nd February 2011
1LAND TRANSACTION RETURN
2ADDITIONAL DETAILS ABOUT THE LAND
3ADDITIONAL DETAILS ABOUT THE TRANSACTION, INCLUDING LEASES
Explanatory note
(This note is not part of the Regulations)
These Regulations provide new forms for SDLT 1, 3 and 4 (“land transaction returns” within the meaning of Schedule 10 to the Finance Act 2003) in connection with land transactions for the purposes of stamp duty land tax.
Regulation 1 provides for the citation, commencement and interpretation of these Regulations.
Regulation 2 substitutes new forms SDLT 1, 3 and 4 for those previously prescribed by Schedule 2 to the Stamp Duty Land Tax (Administration) Regulations 2003 (S.I. 2003/2837).
Regulation 3 makes transitional provisions, saving the validity of the previous form of land transaction returns, so that such documents may be delivered to HM Revenue and Customs at any time before 4th July 2011.
A full and final Impact Assessment has not been produced for this instrument, as a negligible impact on the private and voluntary sectors is foreseen.