The Value Added Tax (Amendment) (No. 3) Regulations 2009
S.I. 2009/1967 · Made 21 July 2009
Value Added Tax
Made 21st July 2009
Laid before the House of Commons 22nd July 2009
Coming into force 15th August 2009
The Commissioners for Her Majesty’s Revenue and Customsf1 make the following Regulations in exercise of the powers conferred by sections 6(14) and 35(2) of the Value Added Tax Act 1994f2.
Annotations to the whole text
Footnotes
- f1
-
Section 96(1) of the Value Added Tax Act 1994 (c. 23) defines “the Commissioners” as meaning the Commissioners of Customs and Excise. The functions of the Commissioners of Customs and Excise were transferred to the Commissioners for Her Majesty’s Revenue and Customs by section 5(2) of the Commissioners for Revenue and Customs Act 2005 (c. 11). Section 50(1) of that Act provides that a reference to the Commissioners of Customs and Excise shall be taken as a reference to the Commissioners for Her Majesty’s Revenue and Customs.
- f2
Contents
- 1Citation and commencement
- 2Amendment of the Value Added Tax Regulations 1995
- 3Amendment of Part 11 of the Regulations (time of supply and time of acquisition)
- 4Amendment of Part 11 of the Regulations (time of supply and time of acquisition)
- 5Amendment of Part 11 of the Regulations (time of supply and time of acquisition)
- 6Amendment of Part 11 of the Regulations (time of supply and time of acquisition)
- 7Amendment of Part 23 of and Schedule 1 to the Regulations (refunds to “do-it-yourself” builders)
- 8Amendment of Part 23 of and Schedule 1 to the Regulations (refunds to “do-it-yourself” builders)
- 9Amendment of Part 23 of and Schedule 1 to the Regulations (refunds to “do-it-yourself” builders)
- Signature
- Schedule
- Form No. 11A: VAT refunds for DIY housebuilders - Part Form No. 11A: VAT refunds for DIY housebuilders -
- Form No. 11B: VAT refunds for DIY housebuilders - Part Form No. 11B: VAT refunds for DIY housebuilders -
- Explanatory note
1Citation and commencement
These Regulations may be cited as the Value Added Tax (Amendment) (No. 3) Regulations 2009 and come into force on 15th August 2009.
2Amendment of the Value Added Tax Regulations 1995
The Value Added Tax Regulations 1995f1 are amended as follows.
3Amendment of Part 11 of the Regulations (time of supply and time of acquisition)
In regulation 84(5)(e)f1, for the words from “of the” to the end, substitute—
“of the Taxes Actf2; but this is subject to sub-paragraph (f);
(f)a company is not connected with another company only because both are under the control of—
(i)the Crown,
(ii)a Minister of the Crown,
(iii)a government department, or
(iv)a Northern Ireland department;
(g)“company” and “control” have the same meaning as in section 839 of the Taxes Actf3.”.
4Amendment of Part 11 of the Regulations (time of supply and time of acquisition)
In regulation 93(15)f1, after “Taxes Act” insert “; but this is subject to paragraph (16).”.
5Amendment of Part 11 of the Regulations (time of supply and time of acquisition)
After regulation 93(15) insert—
“(16)For the purposes of this regulation—
(a)a company is not connected with another company only because both are under the control of—
(i)the Crown,
(ii)a Minister of the Crown,
(iii)a government department, or
(iv)a Northern Ireland department; and
(b)“company” and “control” have the same meaning as in section 839 of the Taxes Act.”.
6Amendment of Part 11 of the Regulations (time of supply and time of acquisition)
For paragraph (4) of regulation 94Bf1 substitute—
“(4)For the purposes of paragraph (2)—
(a)any question whether one person is connected with another shall be determined in accordance with section 839 of the Taxes Act;
(b)a company is not connected with another company only because both are under the control of—
(i)the Crown,
(ii)a Minister of the Crown,
(iii)a government department, or
(iv)a Northern Ireland department;
(c)“company” and “control” have the same meaning as in section 839 of the Taxes Act; and
(d)“undertaking” and “group undertaking” have the same meaning as in section 1161 of the Companies Act 2006f2.”.
7Amendment of Part 23 of and Schedule 1 to the Regulations (refunds to “do-it-yourself” builders)
In regulation 201(a), for the words “the form numbered 11 in Schedule 1 to these Regulations” substitute “the relevant form for the purposes of the claim”.
8Amendment of Part 23 of and Schedule 1 to the Regulations (refunds to “do-it-yourself” builders)
After regulation 201 insert—
“201A.The relevant form for the purposes of a claim is—
(a)Form 11A in Schedule 1 to these Regulations where the claim relates to works described in section 35(1A)(a) or (b) of the Actf1;
(b)Form 11B in Schedule 1 to these Regulations where the claim relates to works described in section 35(1A)(c) of the Act.”.
9Amendment of Part 23 of and Schedule 1 to the Regulations (refunds to “do-it-yourself” builders)
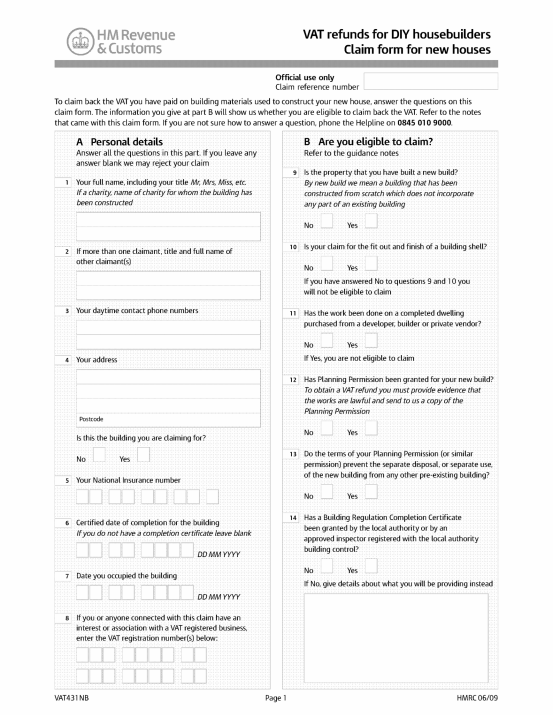
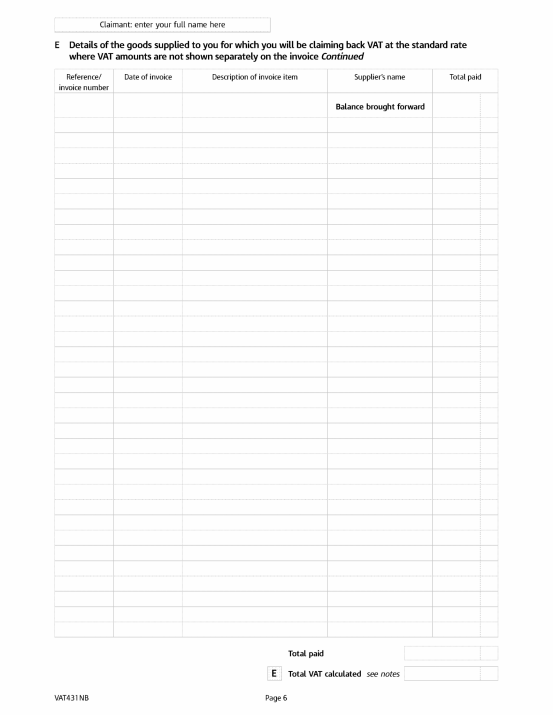
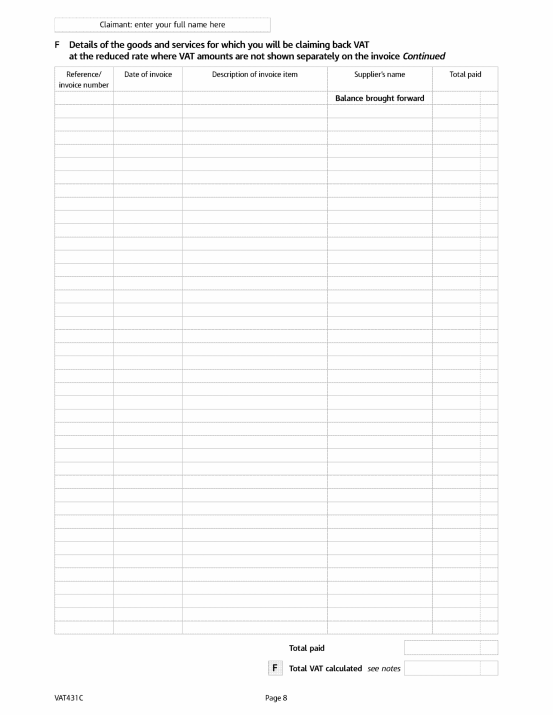
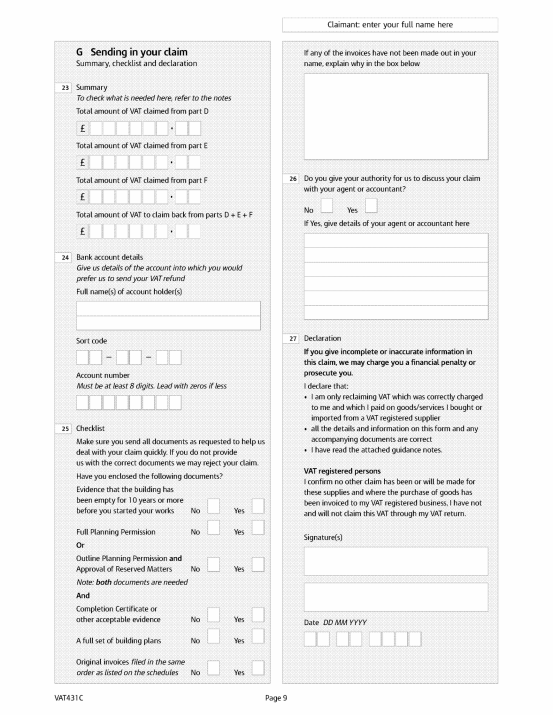
In Schedule 1, for the form numbered 11 (VAT refunds for DIY builders) substitute the forms numbered 11A (VAT refunds for DIY housebuilders – Claim form for new houses) and 11B (VAT refunds for DIY housebuilders – Claim form for conversions) contained in the Schedule to these Regulations.
Signature
Bernadette Kenny
Steve Lamey
Two of the Commissioners for Her Majesty’s Revenue and Customs
21st July 2009
Form No. 11A: VAT refunds for DIY housebuilders -



Form No. 11B: VAT refunds for DIY housebuilders -


Explanatory note
(This note is not part of the Regulations)
These Regulations amend the Value Added Tax Regulations 1995 (1995/2518) (“the Regulations”).
Regulations 3 to 5 amend regulations 84(5)(e) and 93(15) and insert regulations 84(5)(f) and (g) and 93(16) so that, when applying section 839 of the Income and Corporation Taxes Act 1988 (c. 1) (“the Taxes Act”), a company is not connected with another company for the purposes of regulations 84 and 93 only because both are under the control of the Crown, a Minister of the Crown, a government department or a Northern Ireland department.
Regulation 6 substitutes regulation 94B(4) so that, for the purposes of regulation 94B(2), any question whether one person is connected with another will be determined in accordance with section 839 of the Taxes Act but subject to the qualification that a company is not connected with another company for the purposes of that regulation only because both are under the control of the Crown, a Minister of the Crown, a government department or a Northern Ireland department. Regulation 94B(4)(d) defines “undertaking” and “group undertaking”.
Regulations 7 and 8 amend regulation 201(a) and insert regulation 201A so that a claim for refund of VAT under section 35 of the Value Added Tax Act 1994 (c. 23) (refund of VAT to persons constructing certain buildings) must be made on Form 11A or Form 11B in Schedule 1 to the Regulations. Form 11A must be used for refunds in respect of works relating to the construction of building designed as a dwelling or number of dwellings or for use solely for certain residential or charitable purposes. Form 11B must be used for refunds in respect of works relating to the conversion of a non-residential building or a non-residential part of a building into a building designed as a dwelling or number of dwellings or for use solely for certain residential purposes.
Regulation 9 and the Schedule to these Regulations amend Schedule 1 by substituting Forms 11A and 11B for Form 11.
A full and final Impact Assessment has not been produced for this instrument as a negligible impact on the private or voluntary sectors is foreseen.