The Value Added Tax (Amendment) Regulations 2001
S.I. 2001/630 · Made 1 March 2001
VALUE ADDED TAX
Made 1st March 2001
Laid before the House of Commons 2nd March 2001
Coming into force 1st April 2001
The Commissioners of Customs and Excise, in exercise of the powers conferred on them by sections 16(1) and 25(1) of, and paragraph 2(1) and (11) of Schedule 11 to, the Value Added Tax Act 1994f1 and of all other powers enabling them in that behalf, hereby make the following regulations:
Annotations to the whole text
Footnotes
- f1
-
1994 c. 23; section 96(1) defines “the Commissioners” as meaning the Commissioners of Customs and Excise and “regulations” as meaning regulations made by the Commissioners.
Contents
- 1Regulation 1
- 2Regulation 2
- 3Regulation 3
- 4Regulation 4
- 5Regulation 5
- 6Regulation 6
- Signature
- Schedule Schedule
- Explanatory note
1
These Regulations may be cited as the Value Added Tax (Amendment) Regulations 2001 and shall come into force on 1st April 2001.
2
Amend the Value Added Tax Regulations 1995f1 as follows.
3
In regulation 120(2)(a), omit—
“(ii)Articles 130 to 136 (processing for free circulation),”.
In regulation 120(2)(b), omit—
“(ii)Articles 650 to 669 (processing for free circulation),”.
4
Regulation 3 above has effect in relation to goods which are imported on or after 1st April 2001.
5
At the end of regulation 120(2)(b)(iv), omit the word “and”.
In regulation 120(2)(b)(v), insert the following after “(returned goods)”—
“, and
- (vi)
Articles 589 and 709 (compensatory interest)”.
6
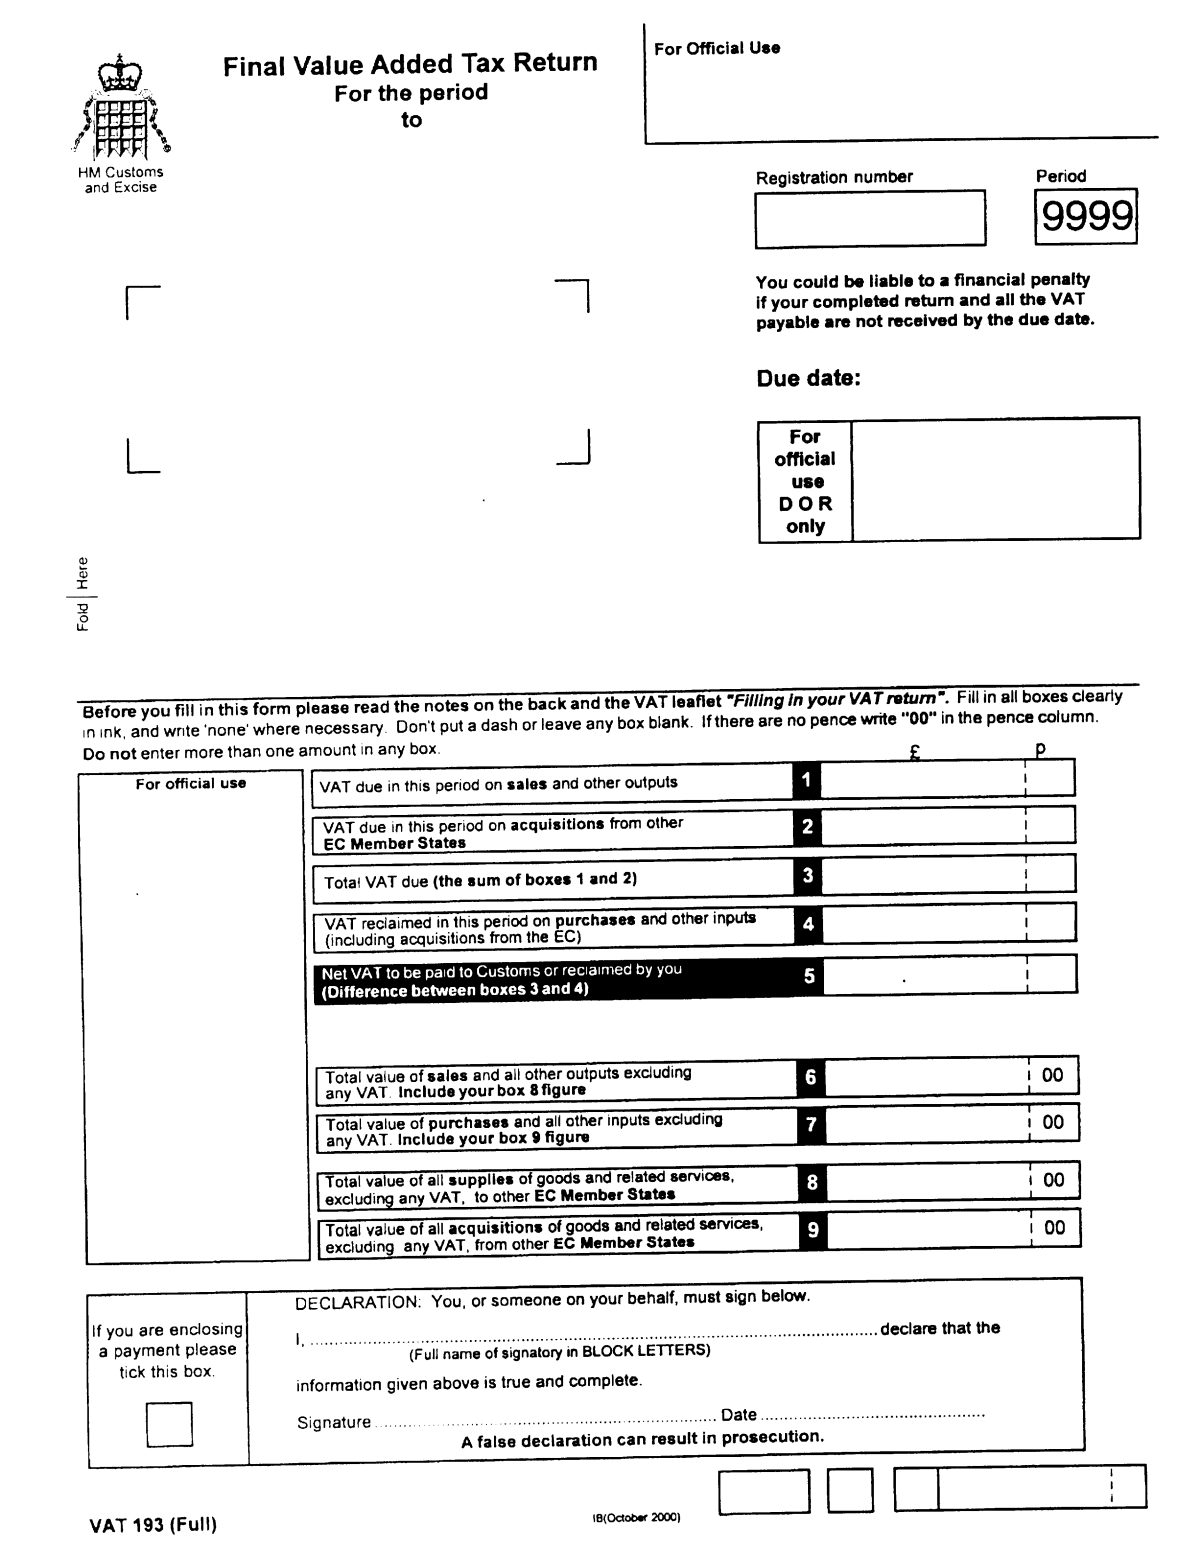
In Schedule 1, for forms numbered 4 and 5 substitute respectively forms numbered 4 and 5 in the Schedule to these Regulations.
Signature
Mike Norgrove
Commissioner of Customs and Excise
New King’s Beam House
22 Upper Ground
London
SE1 9PJ
1st March 2001
Form No. 4

Form No. 5
Explanatory note
(This note is not part of the Regulations)
These Regulations, which come into force on 1st April 2001, amend the Value Added Tax Regulations 1995f1 (the “principal Regulations”).
Value Added Tax (“VAT”) charged on the importation of goods from outside the member States is payable as if it were a duty of customs. Therefore relevant customs legislation applies to import VAT unless it is excepted or adapted by regulations (or there is a contrary intention)f2.
Regulation 3 removes the Community legislation associated with processing under customs controlf3 from the existing lists of Community customs provisions which are excepted from applying to import VATf4. The result of the amendment is that the import VAT on goods under processing for customs control becomes due at the same time as customs duty, thus implementing the UK’s obligations under Article 10(3) of the Sixth VAT Directivef5.
Regulation 4 ensures that goods on which import VAT has been charged before 1st April 2001 are not chargeable to VAT again on release for free circulation.
Regulation 5 adds the Community legislation that charges compensatory interest on customs debtsf6 to the lists of excepted customs legislation. No compensatory interest is therefore chargeable on the import VAT element of a customs debt.
Regulation 6 amends Schedule 1 to the principal Regulations by substituting revised Forms 4 and 5, the Value Added Tax Return and Final Value Added Tax Return respectively. The revised forms omit a box which, in the former version, required those completing the forms to declare which, if any, VAT retail scheme had been used during the period covered by the return.